No More Mr. NICE Guy

NICE is an acronym coined by former Bank of England Governor Mervyn King to describe the “non-inflationary continuous expansion” experienced by the UK economy in the 1990s. With the benefit of hindsight, we could say that the last four decades were “NICE” for global investors. Commentators would struggle to find a better adjective to characterize a 15% decline in treasury yields and near 40-fold increase in the stock market since the early 1980s. NICE indeed.

This remarkable period experienced by the last few generations of investors could be attributed to a range of factors including:

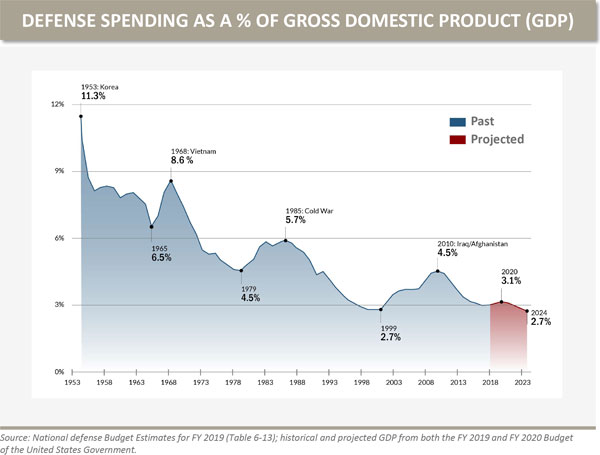
  • The so-called “peace dividend” upon the dissolution of the Soviet Union and the end of the Cold War. The opening of a unipolar world allowed supply chains to lengthen and global specialization to flourish to a degree never before seen. A less hostile world freed up fiscal capacity as US defense spending fell from 5.7% of GDP in 1985 to 2.7% today.
  • The disinflationary impact of China opening to the global economy resulted in a massive rise in Chinese labor productivity which drove a 44-fold increase in Chinese per-capita GDP since 1981. China quite literally exported disinflationary growth to the world by nature of mercantilist policies and low-cost production.
  • Technology similarly enhanced productivity in a non-inflationary manner with the advent of the internet, email, cellular telephones and ever-expanding computing power.
  • Demographics were conducive to non-inflationary economic growth as the bulk of the demographic distribution was employed with the labor force participation rate peaking in the late-1990’s.
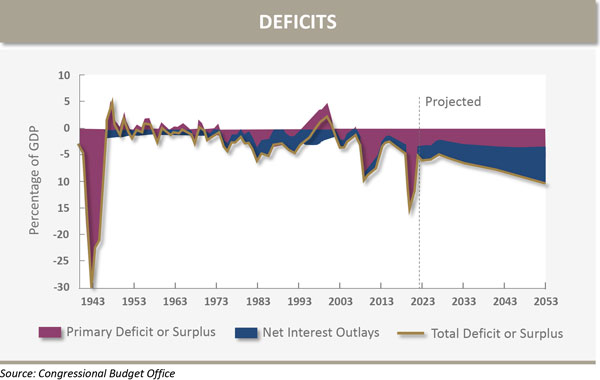
  • Debt and deficits were comparatively low allowing for traditional monetary policy to influence the business cycle through adjustments to the cost of capital in a largely credit-driven economy. More to this point, the abovementioned disinflationary forces were so strong during the NICE years that central bankers became conditioned to quickly intervene in times of market stress with essentially no immediate negative repercussions.

The above list is just a small smattering of the macroeconomic forces that suppressed inflation and simultaneously turbocharged global productivity and economic growth since the early 1980s, resulting in an unprecedented boon to asset owners.

A several decade period of stable inflation and growth was a historical anomaly, and it took a confluence of forces, many of which are unlikely to be repeated, to create the NICE years. In fact, several investor-friendly structural forces are beginning to show signs of reversing themselves.

Specifically:

  • The apparent shift towards geopolitical multi-polarity and the incipient rise of protectionism. Recent geopolitical tensions signal an abrupt end to the “peace dividend,” and it’s fair to assume that defense spending is likely to increase adding further pressure to fiscal deficits.
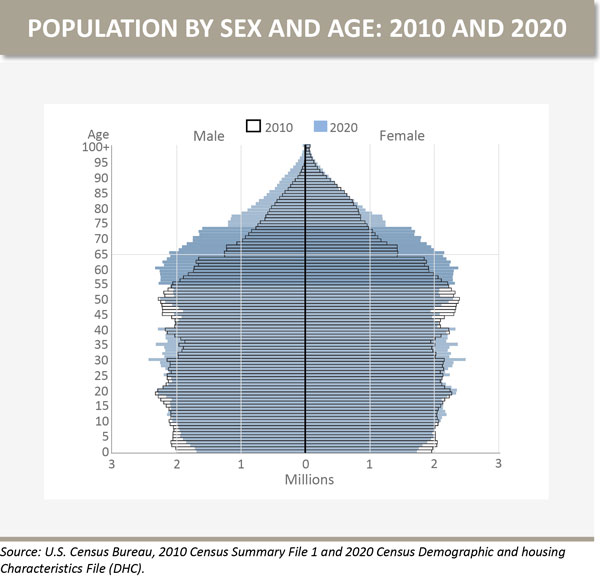
  • ​Demographic impacts on inflation are contentious amongst market prognosticators, but I suspect the continuation of the great retirement will have inflationary effects on the economy. Baby Boomers are currently the largest and wealthiest demographic cohort by far. It seems likely that Boomer demand for goods and services, especially healthcare, will remain strong despite the diminished workforce retirees leave behind. Boomer spending without contributing roughly similar economic productivity may drive up the cost of goods and services in real terms.
  • Commodity prices are likely to increase in the coming decades leading directly to higher prices and weighing on economic growth and productivity. The demand for natural resources appears set to increase thanks to a rising standard of living in the emerging world, the developed world’s desire to transition to green technology and the massive infrastructure build out required to power artificial intelligence. These forces are conspiring after decades of underinvestment in crucial natural resources. The lead times to bring new supply on-line and the political unpopularity of resource extraction will likely result in a delayed supply response to rising demand meaning commodity prices are biased to go higher.
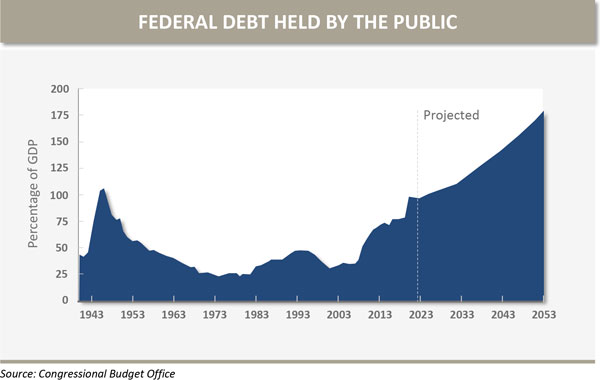
  • Last year we introduced the idea of Fiscal Dominance here. History suggests that US debt and deficit levels may have crossed the point of no return as the effects of fiscal policies now swamp central bankers’ ability to titrate inflation via their monetary policy tools. The only obvious resolution to fiscal dominance is a significant and concurrent cut in entitlements and defense spending; something so unlikely and politically untenable as to be dismissed out of hand. This being the case, the most likely path forward for developed economies is ever more financial repression and currency debasement; two of the largest but least understood risks facing long-term investors.
The emerging macroeconomic backdrop is as uncertain as ever. “Hard landing,” “stagflation,” Mises’ “crack-up boom”; we have no way of knowing ex ante what the future holds for investors. That said, the odds seem stacked against a repeat of 40 more NICE years. The abovementioned evolution in structural forces will likely drive higher future volatility in both growth and inflation. Such elevated macroeconomic volatility necessitates a more balanced, dynamic approach to portfolio construction than the current “60/40,” “buy-and-hold” orthodoxy.

The Oxford Investment Fellows view asset classes through the lens of sensitivity to growth and inflation. Different asset classes have different response functions to rising or falling growth and inflation. Armed with an appreciation of these sensitivities, we seek to assemble asset allocations for clients with an eye towards balancing risk across assets and strategies meant to thrive in different macroeconomic regimes. Such portfolio balance, while often sub-optimal in any single state of the world, ensures robust compounding of capital across meaningful time frames. This more balanced approach sacrifices the chance of being “precisely right” in exchange for taking “precisely wrong” off the table, a prudent strategic framework in an uncertain world.

The information contained in this report is confidential and proprietary to Oxford and is provided solely for use by Oxford clients and prospective clients. The opinions expressed are those of Oxford Financial Group, Ltd. The opinions are as of date of publication and are subject to change due to changes in the market or economic conditions and may not necessarily come to pass. The information in this presentation is for educational and illustrative purposes only and does not constitute investment, tax or legal advice. Tax and legal counsel should be engaged before taking any action. OFG-2406-10
529 Plans – How They Look Today

by: Susan Hagley, MST
Senior Wealth Strategist

The cost of education is notoriously high, leaving some families wondering about the best strategy to save for these expenses. 529 plans have long been a popular education savings vehicle. Unlike a traditional investment savings account, contributions grow tax-free and withdrawals are tax-free when used for qualified education expenses.

But 529 plans also came with significant drawbacks to consider, including tax and penalties on ineligible expenses and restrictions on leftover funds. These drawbacks created uncertainty about how much to fund a 529 plan and what happens to unused funds. After all, there are many circumstances which may not be anticipated, such as scholarships, public vs. private school or the beneficiary of the account deciding not to go to college.

In recent years, however, changes to federal tax law have significantly improved the flexibility of 529 plans, making them an even more attractive option for families to save for education expenses. This article will discuss how to take advantage of these new rules.

The Basics

A 529 plan is a tax-advantaged savings plan designed to help families save for future education expenses. Contributions to a 529 plan grow tax-free, and withdrawals used for qualified education expenses are also tax-free at the federal level. Some states offer additional tax benefits, such as deductions or credits for contributions.

Funds from a 529 plan can be used for qualified education expenses at eligible institutions, including four-year colleges and universities, community colleges, trade, technical and vocational schools, both in the United States and abroad. If funds from a 529 plan are withdrawn for non-qualified expenses, the earnings portion of the withdrawal may be subject to income tax and a 10% penalty.

The student is the beneficiary of the 529 account and not the owner. The parent, or whoever sets up the account, is the owner and ultimately controls the distribution of the money. If the student does not use any or all of the funds, the remaining funds will remain under the owner’s control. One option for the owner is to transfer all or part of the unused funds to a 529 plan for another child or qualified family member.

529 plans offer flexibility in terms of who can contribute, how much can be contributed and how the funds can be used. There are no income limits for contributing to a 529 plan, and contributions can be made by anyone, not just the account owner. Aggregate contribution limits vary depending on the state but range from $235,000 to over $560,000.

Recent Changes

In recent years, there have been significant changes in the federal law governing 529 plans. It’s important to make sure that the state in which your plan is governed has also adopted the same law.

In 2017, the Tax Cuts and Jobs Act expanded 529 plans to include tuition at K-12 schools. Previously, 529 plans were reserved for postsecondary education expenses. Now, owners can make tax-free withdrawals from a 529 account to pay for tuition at K-12 schools. These withdrawals are limited to $10,000 per year per child.

In 2019, there were changes to 529 rules under the SECURE Act to expand the definition of qualified expenses. First, 529 account proceeds can now be used to pay off some student loan debt for the account beneficiary and their siblings. This is limited to a lifetime maximum of $10,000 per individual. Keep in mind that if you make a student loan payment with a distribution, you cannot then claim a student loan interest deduction.

In addition, under the SECURE Act, 529 funds can now be used to pay for the fees, books, supplies and equipment required to participate in an apprenticeship program that is registered and certified with the U.S. Secretary of Labor. This change broadens the scope of eligible institutions, which reduces the risk that your 529 savings will not be utilized if the student decides to pursue a vocational program.

The CARES Act of 2021 included an update to streamline how financial aid is determined and administered. One significant change is that the FAFSA (Free Application for Federal Student Aid) no longer requires students to report distributions from a 529 plan owned by a non-parental figure such as a grandparent. Previously, these distributions were considered untaxed income to the student and had to be reported on the FAFSA. This change removed the so-called “grandparent trap” and improves the student’s eligibility for financial aid.

Finally, in 2022, the SECURE 2.0 Act includes a provision allowing tax-free rollovers from 529 plans to a Roth IRA for the beneficiary effective in January 2024. Previously, the remaining 529 plan funds could only be used by another related beneficiary or withdrawn by the original beneficiary subject to a 10% penalty and income tax on the investment gain.

There are several important limitations to keep in mind under the SECURE 2.0 Act:

  • The Roth account must be in the 529 plan beneficiary’s name (not the owner, if different).
  • To prevent funding a 529 account for the purpose of immediately transferring the funds to a Roth IRA, the 529 plan account must have been in existence for a minimum of 15 years before rolling the funds to a Roth account. (More guidance is expected from the IRS as to whether a change in 529 beneficiary triggers a new 15-year time period.) In addition, contributions and earnings made within the last five years cannot roll over to a Roth account.
  • The maximum lifetime Roth rollover amount is $35,000 per beneficiary. This amount is not indexed for inflation. (More guidance is expected from the IRS as to whether this limitation also applies to 529 account owners.)
  • The Roth rollover is also limited to the annual Roth IRA limit. For example, the 2024 IRA contribution limit is $7,000 per year for individuals under age 50. In addition, the amount eligible for rollover is reduced by any IRA contributions made that year.
  • The beneficiary must qualify for making a Roth contribution for the year by having compensation at least equal to the amount being rolled over. Though, interestingly, the AGI limitations do not apply.

Estate Planning with 529 Plans

Funding education expenses through a 529 plan can be a meaningful way for wealthy families to leave a legacy and support the educational goals of future generations. By earmarking funds specifically for education, families can ensure that their wealth has a lasting impact on the academic success and opportunities of their descendants.

Contributions to a 529 plan qualify for the annual gift tax exclusion, which allows donors to gift up to a certain amount per beneficiary each year without triggering gift tax consequences. As of 2024, this exclusion amount is $18,000 per year per beneficiary.

Additionally, donors can elect to treat 529 plan contributions of up to five times the annual exclusion amount ($90,000 for an individual or $180,000 for married couples) as if they were made over a five-year period without utilizing gift tax exemption.

While the donor retains control of the 529 plan assets, they can also desaignate a successor account owner and change the beneficiary if needed. This allows for flexibility in estate planning strategies and the ability to adapt to changing circumstances or preferences.

Alternatives to 529 Plans

While this article focuses on 529 plans and recent changes made to federal law, there are alternative strategies which may be used in conjunction with, or instead of, a 529 plan. Some examples include an investment account, Roth IRA, UGMA/UTMA, direct tuition payments, and a trust. Each option has its own set of benefits and limitations to consider.

One notable alternative for wealthy families is direct tuition payments. Tuition payments made directly to the educational institution are not treated as taxable gifts, so tuition can be paid without using any annual exclusion or the gift tax exemption. This rule generally does not extend to payments for other expenses, such as room and board.

Another alternative is a Gift Trust, which may be set up for a single beneficiary or as a multigenerational trust. A Gift Trust does not offer the income tax advantages of a 529 plan. There is however, more flexibility in how you can draft a Gift Trust to meet your goals and objectives. Unlike a 529 plan, there is no limit on the aggregate amount which may be gifted to the trust, there is more flexibility in making investment decisions and there are less restrictions on the use of the assets gifted. A Gift Trust could be funded with annual exclusion gifts and/or a gift utilizing your exemptions. The current gift/estate and GST exemption levels of $13,610,000 are historically high and set to return to previous levels on December 31, 2025. This may be an opportunity to use some of your exemptions before they are reduced.

Conclusion

529 plans have long been an attractive way to save for daunting college costs. Recent legislation has amplified their versatility and reduced uncertainty around 529 plan funds. Owners now have more control and flexibility over the disposition of the funds, including new options for the use of unused funds. Further guidance from the IRS may clarify or change the interpretation of new legislation. Your Oxford team of advisors partner with your tax and legal advisors to implement the optimal strategy.

The information contained in this report is confidential and proprietary to Oxford and is provided solely for use by Oxford clients and prospective clients. The opinions expressed are those of Oxford Financial Group, Ltd. The opinions are as of date of publication and are subject to change due to changes in the market or economic conditions and may not necessarily come to pass. The information in this presentation is for educational and illustrative purposes only and does not constitute investment, tax or legal advice. Tax and legal counsel should be engaged before taking any action. OFG-24005-2

The Adaptable Spousal Lifetime Access Trust

“All failure is failure to adapt, all success is successful adaptation.” – Max McKeown, Adaptability: The Art of Winning in an Age of Uncertainty.

This quote from the English writer and researcher of innovation strategy, Max McKeown, applies ironically well to modern day trust structures. While ‘innovative estate planning’ may seem like an oxymoron, a good estate plan should indeed be innovative and designed to adjust to a family’s evolving financial circumstances. Within an estate plan, a truly successful trust is one that will adapt.

A Spousal Lifetime Access Trust (SLAT) is such a trust. The SLAT is an ideal vehicle to embed flexibility into a family’s estate plan, while allowing for significant multi-generational estate tax savings.

Typically, a SLAT is funded during life by one spouse for the benefit of the other spouse, as well as potentially children, grandchildren and even future descendants. The SLAT removes the assets from both the grantor’s and the beneficiary spouse’s estates, providing an estate ‘freeze’ because the gifted assets grow outside the taxable estate.

A key advantage of a SLAT is that the beneficiary spouse may still receive income and distributions from the trust, providing the couple with contingent access to trust assets during their lives. For SLATs structured properly and utilizing the laws of key ‘trust friendly’ states, an independent Trust Protector may later add additional contingent beneficiaries which may include the grantor as well.

As such, a SLAT is a good option for families who would like to make lifetime gifts to utilize at least one (or both) of their gift/ estate and, perhaps, generation-skipping transfer (GST) tax exemptions, but are concerned about losing all access to the trust assets or depleting their current or future income.

Tax reform doubled the federal gift/estate and GST exemptions to $13.61 million per person for 2024. This increased exemption, however, is due to expire December 31, 2025, and is also vulnerable to further tax law changes. A SLAT is ideal for families concerned they may lose the opportunity to make larger gifts should the exemption levels be reduced in the future.

WHICH ASSETS ARE RIGHT FOR A SLAT?
As a general rule, a SLAT should be funded with assets that are expected to appreciate significantly over time, thereby enhancing the growth of wealth in the tax-advantaged SLAT and not in the taxable estate.

A SLAT is also an ideal vehicle to hold life insurance on the grantor’s life. During the grantor’s lifetime, the trustee can take a loan or cash withdrawals from the policy to provide the trust with liquidity for distributions to supplement income or to fund other financial goals.

Upon the grantor’s death, the death benefit and other SLAT assets continue to provide for the beneficiary spouse and family and are kept outside of the grantor’s taxable estate. Upon the beneficiary spouse’s passing, proceeds can enhance legacy wealth and provide for future generations and can be used to lend money to the grantor’s estate to offset estate tax.

THE DYNASTY SLAT
A SLAT can also be designed as a Dynasty Trust when created in a jurisdiction that allows trusts to extend in perpetuity. A Dynasty SLAT is designed to benefit the family as well as multiple future generations, providing an effective way to utilize the GST tax exemption.

With this type of trust, the couple captures the use of their GST tax exemptions along with all of the other advantages of a traditional SLAT.

MAXIMIZING TAX AND FLEXIBILITY PROVISIONS

  1. Estate Tax Advantage: The SLAT is structured as an irrevocable trust. As such, upon funding (with assets held in the individual name of the grantor), the assets are removed from the grantor’s estate and are also not included in the spouse’s taxable estate. Note, the transfer of assets to a SLAT is a gift and will utilize the grantor’s gift/estate exemption. Also, spouses may not create ‘identical’ SLATs or assets will be taxed in their respective estates.
  2. Spousal and Beneficiary Provisions: The spouse has a lifetime interest which can be designed as either required or discretionary income or income/principal distributions, or as unitrust payments. Children and grandchildren may also be named as current beneficiaries, or their interest may begin at the spouse’s death as remainder beneficiaries.
  3. Maximizing Tax Impact: Adding a power to substitute assets enables ‘basis planning’ to mitigate capital gain tax and also ensures that the most rapidly appreciating assets are held in the tax-advantaged SLAT, thereby maximizing the estate tax savings.
  4. Flexibility Provisions: The beneficiary spouse can be given a limited power of appointment to redirect assets among a class of recipients, generally descendants, in order to create flexibility for unknown future circumstances.
  5. Favorable Grantor Trust Status: The trust will be taxed as a grantor trust as long as the beneficiary spouse is living, thereby protecting the trust assets from being depleted by taxes and allowing the grantor to make tax payments on behalf of the trust without being considered a taxable gift. Certain provisions can be included to allow ongoing grantor trust status even if the beneficiary spouse predeceases the grantor.
  6. Trustee: The grantor may not serve as Trustee, but the spouse may, provided the power to make distributions to him or herself are restricted to an ascertainable standard, i.e., amounts needed for health, education, maintenance and support.
  7. Divorce or Death of Spouse: To mitigate concerns, the SLAT can be drafted to include only a ‘current’ spouse and can be established in a jurisdiction that enables a Trust Protector to have the power to add beneficiaries, including a future spouse.

A SLAT provides families with an opportunity to take advantage of the current larger exemption amounts while leaving a window open for access to the trust assets to meet the income needs of the family. This adaptable tool in the planner’s toolbox requires the thoughtful input of the family’s entire team of advisors. Your Oxford advisor will work with your team to coordinate the optimal solution for your family.

Oxford Financial Group, Ltd. is an investment adviser registered with the U.S. Securities and Exchange Commission. Registration does not imply a certain level of skill or training. More information about Oxford Financial Group’s investment advisory services can be found in its Form ADV Part 2, which is available upon request. The information in this presentation is for educational and illustrative purposes only and does not constitute tax, legal or investment advice. Tax and legal counsel should be engaged before taking any action. OFG-2404-66

The Future of Planning for the Well-Planned

“Good fortune is what happens when opportunity meets with planning.” – Thomas Edison

Congratulations…To the well-guided, well-informed and well-planned families who have utilized their full lifetime estate tax exemptions, known more formally as their Gift, Estate and Generation-Skipping Transfer (GST) tax exemptions.

You have skewed the bell curve for many affluent families seeking to protect their generational wealth.

You understand that the alpha of outperforming the market, owning other appreciating assets or having a successful business can pale in comparison to the 40% haircut your wealth will suffer when it passes to your heirs.

As you certainly know, however, assets remaining in your taxable estate will continue to appreciate, as will your liability to the IRS. While there will likely be several more years of inflation increases in tax exemptions, your future wealth and tax planning must evolve and become more strategic and diligent than ever.

This article summarizes several broad techniques that are highly impactful for the well-planned family, to provide inspiration and vision that you can still fight the good fight to protect your generational wealth, even with little or no remaining lifetime tax exemptions.

ESTATE FREEZING TECHNIQUES
Estate freezing strategies are designed to guard your future appreciation from the estate and GST tax. These strategies can involve one or more of a variety of gifts, sales, annuities and lending transactions.

  1. Gifts and Sales to Capitalized Spousal Lifetime Access Trusts (SLATs) and other Family Trusts
    Many families utilized their full lifetime exemptions to gift assets to a SLAT or other variations of an Irrevocable Grantor Trust. Families still have this same opportunity prior to the anticipated sunset of current laws in December 2025, upon which the exemptions are slated to be essentially cut in half.1

    These families now have an ideal opportunity to sell additional appreciating assets to their funded trusts, in return for non-appreciating promissory notes that can carry the low Applicable Federal Rate (AFR). When properly structured, capital gains are not recognized in this type of sale.

    For further information on this and other benefits of a capitalized family trust, see “Doing Business with Your Family SLATs”, Oxford e.Insights, April 6 2022.

  2. Squeezing the Value of the Remaining Taxable Estate with Valuation Discounts
    Utilization of these gift and/or sale techniques can be further enhanced by taking full advantage of valuation discounts to maximize the number of shares or units of the entity being transferred to the trust, while minimizing the corresponding “purchase price” owed back to the Grantor. The most common types of valuation discounts used in these strategies are discounts for lack of marketability and lack of control. Not only does appreciation of the entity continue outside of the Grantor’s taxable estate, but there is also an immediate net benefit to the trust, which now owns an asset worth more than its corresponding liability.
  3. The Tax Burn
    These types of trusts provide another significant benefit. While most gifts utilize either lifetime exemption or annual gift tax exclusion, these trusts enable the grantor to pay taxes on behalf of the trust, thereby preserving the value of trust assets. These tax-free gifts to future generations are known as the tax burn.
  4. Zeroed-out Gifts: The Grantor Retained Annuity Trust (GRAT) and Charitable Lead Annuity Trust (CLAT)
    Both GRATs and CLATs are designed to redirect future appreciation from the grantor’s taxable estate to a remainder beneficiary, typically a children’s or descendant’s trust. With a GRAT, the lead annuity beneficiary is the grantor for the term of the GRAT.2 With a CLAT, it is a qualified charity.3

    With both, however, the remainder interest is considered a taxable gift, potentially subject to gift tax. This ‘gift’, however, can be reduced to zero by predetermining the lead beneficiary’s annuity payments so that the present value equals (and thereby ‘zeroes-out’) the value of the remainder gift.

STRATEGIES TO ENSURE FULL USE OF EACH EXEMPTION

  1. I Love You, May I Have Your Exemption?
    Let’s talk about your options if you have utilized all of your gift and estate exemption, but your spouse has not and has significant assets in his/her taxable estate. In that scenario, there is opportunity to minimize your family’s potential estate tax liability by taking advantage of strategies for your spouse to use his/her remaining exemption. There are a number of approaches that could be implemented to achieve this goal, but a very common strategy for families in this situation is for the spouse who has not exhausted his/her exemption (“Spouse 1”) to create a SLAT for the other spouse’s (“Spouse 2”) benefit and fully fund it to the extent of his/her remaining exemption. This would remove the assets from Spouse 1’s estate (potentially at a discounted rate), while still allowing Spouse 2 to access the income or principal of the trust if needed. Remember, the gift and estate exemption, GST exemption and annual exclusion limits are applied per person, so it is important to always be sure to exhaust all of these exemptions and exclusions to the extent possible for both spouses.
  2. Making Taxable Gifts to Use Remaining GST Tax Exemption – The Math Works
    Some family members may find they have remaining GST exemption, but no remaining gift exemption to pair with it. They might consider paying gift tax to fund a dynastic trust in order to fully utilize GST exemption, particularly before the December 2025 sunset.

    The math works…Gift tax is a one-time 40% tax, whereas GST exemption will provide estate tax savings for multiple generations, more than making up for the gift tax cost. Further, gift tax is ‘estate exclusive,’ because these tax dollars are removed from the taxable estate. If GST is applied at death, the tax is inclusive in the estate, resulting in a tax on the tax. Lastly, there is no portability for GST tax exemption, making it more precarious whether both spouse’s exemption will ever be fully utilized.

OUR NEXT STEPS AND YOURS
Each year we will present a series of articles on strategies for the ‘well-planned’ family, covering additional topics such as Domestic Asset Protection Trusts (DAPTs) to safeguard wealth, optimizing the annual gift tax exclusion, strategies to save state income tax and crafting an efficient plan to pay any remaining estate tax.

In the meantime, your Oxford team of advisors wish you and yours a very happy and healthy holiday season, and stand ready to consult with you on these topics and all of your wealth planning considerations.

1The Gift and Generation-Skipping Transfer (GST) tax exemptions were $12,920,000 in 2023 and are set to increase to $13,610,000 in 2024.
2The Grantor must survive the term of the GRAT or all assets will come back into the Grantor’s taxable estate.
3With a CLAT, the Grantor is eligible for an upfront charitable deduction for the present value of the charity’s annuity interest.

Oxford Financial Group, Ltd. is an investment adviser registered with the U.S. Securities and Exchange Commission. Registration does not imply a certain level of skill or training. More information about Oxford Financial Group’s investment advisory services can be found in its Form ADV Part 2, which is available upon request. The information in this presentation is for educational and illustrative purposes only and does not constitute tax, legal or investment advice. Tax and legal counsel should be engaged before taking any action. OFG-2404-65

Doing Business with Your Family SLATs

Your SLAT is not a ‘Fund and Done.’ Read on to learn the many ways you can transact business with your new family trust1.

Several factors coalesced in recent years to prompt the funding of new family trusts such as Spousal Lifetime Access Trusts (SLATs) and other types of Irrevocable Grantor Trusts.

  1. Many families, prompted by concern over tax reform, made gifts to such trusts to take advantage of favorable trust laws and elevated gift and generation-skipping transfer (GST) tax exemptions ($13,610,000 per person in 2024). Wealth transfers in excess of these exemptions are taxed at the heavy rate of 40%.
  2. Other families, motivated by appreciating wealth due to strong markets, sought the impact of freezing their future estate tax sooner rather than later. Forward-thinking families also chose to act prior to the sunset of current laws, set for December 31, 2025, whereupon these exemptions are due to be cut essentially in half.

Regardless of the motivation, these families now have an ideal opportunity to transact business with their new (or more fully funded) family trust. They have created and capitalized the ultimate third party for business transactions.

Provided the formalities of a ‘normal course of business’ are followed, their trust may become their family bank, an asset-swapping partner or a purchaser of further assets in return for low interest rate promissory notes. When assets are purchased from properly structured family entities, valuation discounts can further reduce the amount of the family’s remaining taxable estate.

In addition to these generational tax savings strategies, the family’s trust may be structured with a family governance LLC to ensure the Grantor’s legacy footprint is cast deeply for generations to come.

THE FAMILY BANK
Liquidity issues often arise when a family’s balance sheet is heavy with business interest, managed accounts, real estate or private equity, to name a few. Such trusts can make loans to family members without onerous collateral requirements and at the most favorable applicable federal rates (AFR). Further, the trust may make low interest loans to younger generations as they embark on new business ventures, home purchases or other investments, providing the next generation with a leg-up on building their own financial acumen.

A SWAPPING PARTNER
Also known as a Power of Substitution, this power enables the trust grantor to swap assets of equivalent value between their personal balance sheet and the trust, maximizing tax savings impact in two key ways:

  1. Estate Tax Savings: First, because the trust is outside the reach of the 40% estate tax, it should hold the family’s most rapidly appreciating assets. The family’s ‘flat’ assets, such as a non-appreciating promissory note, should be held in the taxable estate where it will not increase estate tax exposure in future years.
  2. Income Tax Savings: Given our current law still allows for a step-up in basis at death to fair market value (FMV), families may at times elect to swap low basis trust assets back into the grantor’s estate. Assets of equivalent value are then transferred into the trust, where they will avoid the 40% estate tax.

A THIRD-PARTY PURCHASER OF FAMILY ASSETS
For affluent families that have already utilized their full gift and GST exemptions, the IRS stands ready to receive their 40% share of the family’s growing balance sheet. This result can be mitigated by the grantor selling additional assets to their capitalized trust in return for low interest, non-appreciating promissory notes, often structured as balloon notes. The family only retains the interest payment from their trust.

While irrevocable for estate tax purposes, these trusts are grantor trusts for income tax purposes. When properly structured, a sale by the grantor does not cause a recognition of capital gains, providing a true ‘have your cake and eat it too’ planning opportunity.

PLANNING IN TANDEM WITH A FAMILY ENTITY
To enhance investment opportunity and family wealth governance, the family may contribute assets to an entity eligible for valuation discounts. The grantor may then sell interest in the entity and take back a promissory note with a lower face value, further reducing taxable wealth. The resulting promissory notes are additional assets that can be contributed to family entities and also potentially entitled to discounts, all with the impact of further reducing the family’s future estate tax.

A TRUSTED BUSINESS PARTNER
When the trust has been thoughtfully crafted with trusted fiduciaries and entity governance, the family is essentially doing business with their most trusted advisors. Your Oxford team brings a bespoke approach to your family’s wealth planning. Together with your team of outside advisors, we show families sophisticated strategies to capitalize on all aspects of their wealth transfer plan, today, tomorrow and for generations to come.

1Such trusts may be known as Intentionally Defective Grantor Trusts (IDGTs) or Intentionally Defective Irrevocable Trusts (IDITs).

Oxford Financial Group, Ltd. is an investment adviser registered with the U.S. Securities and Exchange Commission. Registration does not imply a certain level of skill or training. More information about Oxford Financial Group’s investment advisory services can be found in its Form ADV Part 2, which is available upon request. The information in this presentation is for educational and illustrative purposes only and does not constitute tax, legal or investment advice. Tax and legal counsel should be engaged before taking any action. OFG-2404-67

Charitable Giving Vehicles: Part 2 – Private Foundations

By: Susan Hagley, MST
Senior Wealth Strategist

There are many charitable giving vehicles available to help you carry out your philanthropic goals. In our previous e.Insight, we discussed one of the commonly used options to consider; a Donor Advised Fund. In this Part 2, we will discuss Private Foundations.

Basics
A Private Foundation is a distinct tax-exempt legal entity that is governed by its own set of bylaws to support charitable activities. Private Foundations have more required formalities and costs, but also allow for more flexibility and family control over grantmaking and investment decisions. Private Foundations can be a very powerful charitable tool to promote philanthropy through multiple generations.

Starting a Private Foundation is a more time-intensive process that includes filing an application with the state and IRS to obtain private foundation status. This involves legal and accounting costs to complete the application and filings prior to being approved.

Administration
Once established, Private Foundations typically hire staff or outside advisors to manage the administrative work and investment management for the Foundation. They can also appoint a board of directors (including family members) and are recommended to have regular board meetings, which include recording minutes.

In addition to the general laws that all charities must follow, Private Foundations are subject to complex technical rules. Failure to follow these rules, described below, may result in excise tax penalties:

  1. Self-dealing restrictions between Private Foundation and substantial contributors and disqualified persons
  2. Annual 5% minimum distribution requirement based on the previous year’s net average assets
  3. Limitations on private business holdings
  4. Investments must not jeopardize the carrying out of exempt purposes
  5. Expenditures must further exempt purposes

Grantmaking
Private Foundations offer a wider array of choices in grantmaking compared to Donor Advised Funds (DAFs), which can only issue grants to 501(c)(3) charitable organizations. Private Foundations, for example, may also provide scholarships to individuals, grants to families or individuals for hardships and emergencies, and grants to international organizations. A Private Foundation can also make grants to a DAF or even be converted into a DAF, if specific rules are followed. On the contrary, a Donor Advised Fund can’t make grants to or be rolled into a Private Foundation. The Private Foundation is responsible for legal compliance and due diligence in the grantmaking process.

Privacy
Private Foundations are required to file annual returns, which are available to the public. These returns list foundation assets, contributors and grantees. Therefore, it is not possible to make anonymous gifts.

Contributions and Asset Selection
A Private Foundation can be funded with many different types of assets. For example, donors may gift cash, publicly-traded securities, mutual funds, publicly-traded bonds, art, real property and private equity investments. Unlike a DAF, where the sponsoring organization may limit the type of assets gifted and also usually sells after receiving, a Private Foundation has less restrictions.

One of the most appealing qualities of Private Foundations is the degree of flexibility around investment decisions. This allows Private Foundations to grow their assets in a tax-efficient and dynamic way. A Private Foundation can include private equities in its portfolio, as long as the board follows all of the specific IRS rules and is cognizant of other issues, including liquidity needs and unrelated business income tax. In addition, Private Foundations can invest in Program Related Investments (PRIs). A PRI is a versatile investment that is designed to provide a below-market return back to the Private Foundation, which can then be used for charitable purposes.

Family Engagement
Many donors start a Private Foundation with long-term family engagement in mind. Private Foundations are inherently collaborative because of the required board structure. The family can remain in control through generations by specifically drafting into the organizational documents that family members are to serve on the board of directors. A Private Foundation may hire and compensate family members to provide professional services to the Foundation, provided their compensation is reasonable. The high-level of formality and long-term platform provided by Private Foundations may be attractive to families that want to do something positive, together, for generations to come.

In addition to the board structure, donors may wish to create a Family Philanthropic Mission Statement to memorialize values, experiences and insights. A Family Philanthropic Mission Statement may provide guidelines for grantmaking such as specific causes and geographic areas. It will also ensure that your core vision will guide your family giving now and in the future.

Income Tax Deductions for Taxpayers Who Itemize Deductions
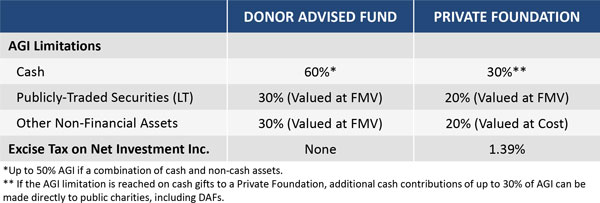
Private Foundations and DAFs are subject to different tax treatment. In Part 1, we compared the income tax deductions. Gifts to private foundations are subject to lower Adjusted Growth Income (AGI) limitations than gifts to a DAF. In addition, private foundations are subject to an annual excise tax of 1.39% on net investment income.

Conclusion
Donor Advised Funds and Private Foundations are commonly used charitable vehicles that may effectively help you reach your philanthropic goals. They offer very different levels of control, flexibility and legacy building. The choice between philanthropic vehicles also does not need to be an either/or decision. Donor Advised Funds can be a great complement to a Private Foundation. When used together, they can be an optimal solution for managing wealth and achieving philanthropic impact.

How do you decide what makes sense for your family? Here are some questions to discuss with your Oxford Advisors to help guide the decision:

  1. What is your giving style?
  2. Do you require more flexibility or control over investments or grantmaking?
  3. How much do you wish to donate?
  4. What level of family involvement do you desire?
  5. Do you want the vehicle to extend through multiple generations?

The information contained in this report is confidential and proprietary to Oxford and is provided solely for use by Oxford clients and prospective clients. The opinions expressed are those of Oxford Financial Group, Ltd. The opinions are as of date of publication and are subject to change due to changes in the market or economic conditions and may not necessarily come to pass. The information in this presentation is for educational and illustrative purposes only and does not constitute investment, tax or legal advice. Tax and legal counsel should be engaged before taking any action. OFG-2401-38

Charitable Giving Vehicles: Part 1 – Donor Advised Funds

By: Susan Hagley, MST
Senior Wealth Strategist

There are many charitable giving vehicles available to help you carry out your philanthropic goals. Two of the more commonly used options to consider are a Donor Advised Fund or a Private Foundation. Both will allow you the opportunity to be more strategic with your charitable giving and to create a philanthropic legacy for your future generations.

In this first email in our two-part series, we will discuss Donor Advised Funds. Understanding the distinct advantages and drawbacks is the key to deciding which vehicle is best suited for your circumstances and goals.

Basics
A Donor Advised Fund (DAF) is a giving account that is housed in a public charity (the sponsoring organization). Donor Advised Funds are a simple and efficient way to make a charitable impact. Donors may contribute assets and receive a current year income tax deduction. The funds can then be invested and grow tax-free while the donor has flexibility to recommend grants to charity over time. This provides families with time to develop a thoughtful giving plan.

Setting up a DAF involves selecting a sponsoring organization (such as a national nonprofit or a community foundation) and completing their requisite form or application. There is generally no cost involved in opening a DAF and it can typically be established and ready in a few days. Once the DAF account is open, the donor makes an irrevocable gift that cannot be returned or used for any purpose other than grantmaking to charities.

Administration
Once established, the sponsoring organization handles the administrative work at a low cost. This includes managing investments, record keeping, tax receipts and grant administration. The donor retains advisory privileges to make grant requests and, in some cases, select an investment advisor. Sponsoring organizations typically have suggested minimum payouts and limits on the length of time without any grants being made. They may also require a grant if the overall fund did not meet its total required payout.

Grantmaking
Donor Advised Funds are required to give to 501(c)(3) public charities. Therefore, they are not able to make grants to private foundations or individuals, such as for scholarships or hardships. They also may not make grants to fulfill multiyear pledges. The DAF sponsoring organization handles the due diligence related to grantmaking. The donor may request grants to specific public charities. Then, the sponsoring organization is responsible for reviewing the grant requests and must approve them before they are made.

Privacy
DAFs provide donors with the ability to make anonymous grants, providing privacy if that is desired. This can be accomplished because DAFs do not have an annual filing requirement, so names of individual donors are not disclosed to the public. In addition, a gift can be presented to the charity disclosing only the name of the sponsoring organization.

Contributions and Asset Selection
When making any gift, asset selection is an important consideration. Ideal assets to gift to a DAF are long-term appreciated securities, especially those with low basis. This is the most tax-efficient method because securities that have been held for more than one year can be donated at their fair market value and it eliminates the capital gains tax on the sale. It also maximizes the charitable dollars available because the DAF is not subject to tax.

The most common assets to gift to a DAF include cash, publicly-traded securities and mutual funds. However, some donors desire to gift complex non-cash assets, such as non-publicly-traded stock or an LLC interest. Key considerations when donating complex assets include whether the supporting organization will accept the asset, if it can be transferred and liquidated, how long the process will take, how soon liquidity is needed and how much an appraisal will cost to determine the fair market value.

Family Engagement
To engage the next generation, donors may wish to create a Legacy Plan for their DAF. Typically, donors act as the primary advisors and appoint their children or loved ones as secondary advisors. Depending on the sponsoring organization, other succession options may include dividing the DAF for individual successors, naming charities as beneficiaries to receive the remaining assets or endowing a DAF to continue making grants to designated charities for a period of time. The Legacy Plan may also include a Family Philanthropic Mission Statement. This allows donors and families to communicate charitable intent and provide guidelines for grantmaking.

Income Tax Deductions for Taxpayers who Itemize Deductions 
Charitable giving is not only a generous and compassionate act, but it also can be an effective tax strategy. Donors who itemize their deductions on their income tax return may qualify for a charitable contribution deduction. The tax deduction is limited to a percentage of your AGI and contributions that exceed these limitations can be carried over in each of the next five years until used. 

DAFs and private foundations are subject to different tax treatment, summarized below. In years you donate a significant portion of income to charity or have a highly appreciated asset to contribute, you may receive a larger tax benefit through the use of a DAF.

Conclusion
Part 2 of this series will discuss private foundations to further help you understand which charitable vehicle may make sense for your family.

The information contained in this report is confidential and proprietary to Oxford and is provided solely for use by Oxford clients and prospective clients. The opinions expressed are those of Oxford Financial Group, Ltd. The opinions are as of date of publication and are subject to change due to changes in the market or economic conditions and may not necessarily come to pass. The information in this presentation is for educational and illustrative purposes only and does not constitute investment, tax or legal advice. Tax and legal counsel should be engaged before taking any action. OFG-2401-35