Section 1202 and Qualified Small Business Stock Overview

Backing a young company is risky, and many startups never deliver a return to the people who fund them. To encourage that risk taking, Congress created a tax incentive in 1993 that rewards those who take the risk and help a company grow. Section 1202 of the Internal Revenue Code allows non-corporate investors and founders to exclude a substantial portion, or potentially all, of their capital gains from federal income tax when selling stock. This is known as Qualified Small Business Stock, or QSBS. For families with significant wealth tied to a privately held business, the exclusion can be one of the more valuable provisions in the tax code; a single successful sale of qualifying stock may shelter millions of dollars of gain. The rules are technical, however. The benefit depends on how the stock was acquired, what kind of company issued it and how long it was held. This overview first explains the core requirements then turns to planning strategies that can extend the benefit further.

Key Requirements and Structure
  • Eligible Taxpayers: Available to individuals, trusts and estates. Partnerships and S corporations may also pass the benefit through to their individual owners under specific conditions.
  • Original Issuance: Stock must be acquired directly from a domestic C-corporation at its original issuance, rather than purchased from another shareholder on the secondary market. While the stock cannot be purchased on the secondary market, QSBS status and the holding period do carry over if the stock is transferred via gift or inheritance.
  • Asset Threshold: For stock issued after July 4, 2025, the corporation’s aggregate gross assets cannot exceed $75 million at all times before the issuance and immediately after the issuance. The limit was previously $50 million.
  • Active Business Requirement: During substantially all the holding period, at least 80% of the corporation’s assets must be used in the active conduct of a qualified trade or business. Businesses in fields such as law, medicine, consulting, financial services and hospitality are excluded.
  • Holding Period and Exclusion Levels:
    • Pre-July 4, 2025 stock: Requires a 5+ year holding period for up to a 100% gain exclusion (the full 100% applies to stock acquired after September 27, 2010; earlier issuances are limited to 50% or 75% exclusions).
    • Post-July 4, 2025 stock: Under the 2025 legislation, known as the One Big Beautiful Bill Act, the exclusion is tiered, allowing a 50% exclusion at three years, a 75% exclusion at four years and a 100% exclusion at five or more years.
  • Gain Caps: The maximum exclusion per taxpayer per issuer is limited to the greater of a $10 million cumulative lifetime cap ($15 million for post-July 4, 2025 stock) OR an annual cap equal to ten times the aggregate adjusted basis of the stock sold during that specific tax year. Basis generally refers to what the investor paid for the shares.

While Section 1202 is a federal tax incentive, each state decides whether to follow it, so state-level conformity varies widely. Some states conform to the federal rules and completely exempt QSBS gains, others partially conform, and some completely decouple from the provision, meaning state income tax may still apply.

Where a state does conform, the federal exclusion generally carries over to the state return. Where it does not, the full gain is taxed at state rates even when no federal tax is due. Currently, several states including California, Alabama, Mississippi and Pennsylvania, do not allow the exclusion and a few other states, such as Hawaii and Massachusetts, conform only in part. New Jersey, long among the non-conforming states, began following the federal rules for tax years beginning on or after January 1, 2026. States can also change course. For example, Oregon decoupled from the exclusion in spring 2026, and New York lawmakers advanced then withdrew a similar proposal. Because many states tie their tax codes to the federal code as of a fixed date, some may also be slow to adopt the 2025 federal changes. What matters is the state where the taxpayer lives when the stock is sold, not where the company is incorporated; a move before a sale or the location of a trust holding the shares can change the result. State treatment should therefore be reviewed with a tax advisor well before any sale.

Maximizing the benefits of QSBS goes beyond simply holding shares for five years. Advanced planning strategies such as deferrals, multiplying exclusions, increasing basis caps and charitable planning may allow qualifying founders and investors to shield even larger portions of wealth from taxes. The four strategies below address each of these in turn.

Advanced QSBS Strategies and Overview
  • Section 1045 Rollovers (Deferrals):
    • A rollover works as an early-exit bridge. If a liquidity event happens before the five-year holding period is met, you can roll over the proceeds into a new qualifying QSBS within 60 days, provided you held the original stock for more than six months.
    • This defers the capital gains tax and preserves your original holding period clock for tax exclusion.
    • For stock issued after July 4, 2025, if a liquidity event occurs at year three or four, founders must weigh whether to take the new partial OBBBA exclusion or use a Section 1045 rollover to defer the entire gain and preserve a path to a 100% exclusion.
  • QSBS Stacking (Multiplying Exclusions):
    • Because the gain cap applies per taxpayer, per issuer, founders can multiply the number of taxpayers, and therefore their exclusion limits, by gifting shares early to irrevocable non-grantor trusts or to family members.
    • Each separate non-grantor trust is treated as an independent taxpayer with its own cap, which is $15 million for stock issued after July 4, 2025. This can multiply the amount of gain eligible for the federal exclusion, although gifts are generally irrevocable, may have gift-tax consequences, and may not be recognized for state tax purposes.
    • Careful trust design is critical. Under IRS anti-abuse rules, multiple trusts with substantially the same grantor and beneficiaries may be treated as a single taxpayer, nullifying the extra exclusions.
  • QSBS Packing (Increasing Basis Caps):
    • The gain cap is limited to the greater of the flat dollar limit or ten times the aggregate adjusted basis of the stock. For stock issued after July 4, 2025, the flat limit is $15 million.
    • Founders can increase their tax basis early on to maximize the 10x basis cap for hyper-growth companies. They might do so through capital contributions or by purchasing shares at fair market value before significant appreciation. However, making additional capital contributions puts more wealth at risk in a concentrated, illiquid asset, and purchasing shares at fair market value requires upfront liquidity that founders may not have.
  • Charitable Remainder Unitrusts (Charitable Planning):
    • Placing QSBS into a charitable remainder unitrust, or CRUT, before a sale generally allows the trust to sell the stock without paying tax on the gain.
    • The proceeds remain inside the trust to pay out an income stream over time and eventually benefit charity. This approach bridges philanthropic goals with tax-free portfolio diversification within the trust. Distributions to the income beneficiary are generally taxed under the trust’s tiered rules, so the gain is typically deferred rather than eliminated, and the donor gives up the opportunity to use the Section 1202 exclusion directly.

Advanced strategies like stacking and rolling over require strict adherence to IRS timelines and corporate documentation, including attestations from the company made at the time the stock is issued. Missteps can easily trigger disqualification or unintended gift-tax consequences. The Oxford team brings deep experience working with families and business owners on their overall planning goals and objectives. In coordination with legal and tax advisors, we apply thoughtful, customized strategies to help clients pursue their financial goals.

Oxford Financial Group, Ltd. (“Oxford”) is a Registered Investment Advisor (“RIA”) with the U.S. Securities and Exchange Commission (“SEC”) and is headquartered in Carmel, Indiana. Registration with the SEC does not imply a certain level of skill or training. Additional information about Oxford, including our Form ADV and Privacy Policy, is available upon request by calling 800.722.2289 or emailing info@ofgltd.com. The content of this presentation is intended for educational and illustrative purposes only. It should not be construed as investment, tax, or legal advice, nor as a recommendation or offer to buy or sell any security or investment product. The strategies referenced above are illustrative in nature and may not be available, suitable or advisable for every individual, entity or transaction. No strategy discussed guarantees the achievement of any tax, estate planning or transaction objective. Tax and legal counsel should be engaged before taking any action. This material has been prepared using original sources believed to be reliable, but no representation is made as to its accuracy or completeness. The views expressed are those of Oxford as of the date of the presentation and are subject to change based on market, regulatory or economic conditions, which may not occur as anticipated. For full disclosures and disclaimers, please visit https://ofgltd.com/home/disclaimers. OFG-2610-53
Oxford Managing Director H. Tyler Rosser Named One of the Best Wealth Managers and Advisors Under 40 in the U.S.

Oxford Financial Group, Ltd. is pleased to announce that Managing Director H. Tyler Rosser, JD, CFP® has been named one of the best wealth managers and advisors under 40 in the United States by InvestmentNews, as part of their 2026 Rising Stars list.

The InvestmentNews Rising Stars list honors professionals who demonstrate strong performance, leadership and commitment in their roles, while contributing beyond their core responsibilities through meaningful initiatives and measurable results. Honorees are selected through a nationwide nomination process and evaluated by an independent panel of industry leaders.

Tyler’s legal background gives him a distinct perspective on the complex, multigenerational planning challenges the families Oxford serves face every day. As a Managing Director at Oxford, he works within the firm’s family office model, partnering with UHNW families, business owners and executives on estate and tax planning, business succession, family governance and philanthropic strategy.

Beyond his client work, Tyler serves on Oxford’s Wealth Council, mentors a junior Oxford associate, teaches Estate and Gift Taxation as an adjunct professor at Indiana University’s Robert H. McKinney School of Law, and contributes to philanthropic planning through his involvement with the Central Indiana Community Foundation and the Indiana University School of Medicine’s Planned Giving Committee.

We congratulate Tyler on this well-deserved recognition. See the full 2026 Rising Stars list.

###
InvestmentNews Rising Stars published October 28, 2026 and were based on nominations submitted by June 12, 2026. Finalists were selected by InvestmentNews with the guidance of an independent advisory panel. H. Tyler Rosser was nominated by Oxford Financial Group, Ltd. Oxford did not pay a fee for inclusion in the ranking. Methodology: Rising Stars 2026: Celebrate excellence in wealth management

Oxford Financial Group, Ltd. (“Oxford”) is a Registered Investment Advisor (“RIA”) with the U.S. Securities and Exchange Commission (“SEC”) and is headquartered in Carmel, Indiana. Registration with the SEC does not imply a certain level of skill or training. Additional information about Oxford, including our Form ADV and Privacy Policy, is available upon request by calling 800.722.2289 or emailing info@ofgltd.com. The content of this communication is intended for educational and illustrative purposes only. It should not be construed as investment, tax or legal advice, nor as a recommendation or offer to buy or sell any security or investment product. Tax and legal counsel should be engaged before taking any action. This material has been prepared using original sources believed to be reliable, but no representation is made as to its accuracy or completeness. The views expressed are those of Oxford as of the date of this communication and are subject to change based on market, regulatory or economic conditions, which may not occur as anticipated. View important disclosures and disclaimers at https://ofgltd.com/home/disclaimers/ OFG-2610-55

Navigating the 2026 Tax Landscape: Your Year-End Tax Planning Guide

Year-end tax planning is a beneficial process for individuals, business owners and investors aiming to optimize their financial standing and minimize overall tax liabilities. As the tax landscape continues to evolve, proactive planning before the conclusion of the calendar year allows taxpayers to take advantage of specific provisions, manage income brackets and maximize deductions and credits.

For the 2026 tax year, navigating the complexities of the tax code requires a highly structured approach due to the passage of the One Big Beautiful Bill Act (OBBBA). This legislation fundamentally changes the year-end playbook, introducing critical new provisions such as a State and Local Taxes (SALT) cap phase-down, a 0.5 percent charitable contribution floor, a 35 percent cap on itemized deduction value, AMT phase-out changes, the Roth catch-up mandate and the end of initial Opportunity Zone deferrals. By evaluating income sources, deduction opportunities, investment strategies and compliance obligations ahead of the December 31 deadline, taxpayers can position themselves advantageously for the upcoming filing season.

One of the fundamental pillars of effective year-end tax planning involves careful management and timing of income and high-earner tax thresholds. Depending on individual circumstances, taxpayers may benefit from either accelerating or deferring income into the next tax year. For individuals anticipating a higher tax bracket in the current year compared to the next, deferring bonuses, capital gains or self-employment income can result in tax savings. Conversely, if future tax rates are expected to increase or if income is projected to be higher in subsequent years, accelerating income might be advantageous. Business owners face similar decisions regarding invoicing clients before year-end or delaying billing to shift revenue recognition into the following fiscal period. Strategic timing may help position income to be taxed at more favorable marginal rates, while remaining attentive to novel income categories, such as the new exemptions for tips, overtime pay, car loan interest and enhanced senior deductions, along with specific adjusted gross income (AGI) phase-out limits established for 2026. High-income earners must remain vigilant regarding the Alternative Minimum Tax (AMT) and the 3.8 percent Net Investment Income Tax (NIIT) on investment earnings, actively managing modified adjusted gross income (MAGI) to prevent unnecessary exposure.

Equally important to income management is the strategic acceleration or deferral of deductible expenses and healthcare accounts. Taxpayers who itemize deductions can often benefit from “bunching” deductible expenses, such as medical costs, charitable contributions and state and local taxes, into a single tax year to surpass the standard deduction threshold. For 2026, the federal standard deductions are adjusted to $16,100 for single filers, $32,200 for married couples filing jointly and $24,150 for heads of household, alongside a temporary senior bonus deduction for adults aged sixty-five and older. Scheduling elective medical procedures, purchasing necessary business equipment or paying upcoming property taxes before the end of the year can successfully push taxpayers past these higher thresholds. Taxpayers should audit their medical Flexible Spending Accounts (FSAs) ahead of December 31 to avoid forfeiting funds under the use-it-or-lose-it rule, while maximizing contributions to Health Savings Accounts (HSAs) to leverage triple tax advantages and above-the-line deductions that reduce AGI.

Retirement account optimization and strict compliance with distribution rules remain important for robust year-end tax strategies. Contributing the maximum allowable amounts to employer-sponsored retirement plans can lower taxable income for the year. Retirees and inherited IRA beneficiaries should calculate and execute Required Minimum Distributions (RMDs) prior to December 31 to avoid excise taxes and penalties. Individuals should also evaluate whether a Roth conversion makes sense for their financial situation, converting traditional pre-tax retirement funds into a Roth account during a year with lower-than-average income to lock in a potentially lower tax rate, allowing future growth and qualified withdrawals to be tax-free. However, taxpayers should generally avoid executing Roth conversions during years with large liquidity events. A conversion in a year of abnormally high income exposes more dollars to AMT and NIIT pitfalls, which can negate the desired rate arbitrage. Because Roth conversions are treated as taxable income in the year they occur, careful calculation of tax brackets is necessary to avoid inadvertently pushing income into a higher marginal bracket or triggering additional surtaxes.

Investment portfolios may also be reviewed as the calendar year draws to a close. Tax-loss harvesting is a technique where investors sell underperforming assets at a loss to offset capital gains realized elsewhere in the portfolio. If capital losses exceed capital gains, up to a specified limit of ordinary income can be offset, providing an additional layer of tax relief. Investors should coordinate harvesting strategies closely with the 20 percent long-term capital gains and NIIT thresholds to maximize efficiency. Investors must also remain mindful of the wash-sale rule, which prohibits purchasing a substantially identical asset within thirty days before or after the sale to claim the loss.

Beyond loss harvesting, 2026 brings critical, time-sensitive deadlines for Opportunity Zones under OBBBA. Gains deferred under the original Qualified Opportunity Fund (QOF) program must be recognized on December 31, 2026, with tax due on the 2026 return, requiring affected clients to plan for liquidity and estimated payments now. Because OBBBA’s permanent Opportunity Zone program applies to investments made after December 31, 2026, gains realized late in 2026 may be eligible for reinvestment in a new-program QOF in 2027 within the standard 180-day window (subject to confirmation with tax counsel). Evaluating dividend distributions and capital gains distributions from mutual funds prior to year-end also helps prevent unexpected tax surprises during tax season.

Charitable giving and wealth transfer strategies offer avenues for philanthropy and tax reduction, though OBBBA introduces significant new parameters for 2026. The headline for year-end giving is the restructuring of charitable deductions. Itemized charitable deductions are now subject to a 0.5 percent of AGI floor, and for taxpayers in the 37 percent bracket, itemized deductions are reduced by 2/37, effectively capping the benefit at 35 percent. Non-itemizers can utilize a new $1,000 (single) or $2,000 (joint) cash deduction, though this cannot be used for gifts to Donor-Advised Funds (DAFs) or private foundations. Because the floor and cap continue in 2027, preventing rate arbitrage between years, the new 0.5 percent floor makes “bunching” several years of giving into a DAF in a single year highly attractive, as the floor is only absorbed once. Donating appreciated securities directly to qualified charitable organizations still allows donors to deduct the full current market value of the assets while entirely bypassing capital gains taxes that would have been incurred upon a direct sale.

For retirees subject to RMDs, utilizing Qualified Charitable Distributions (QCDs) offers a tax-efficient mechanism to fulfill distribution requirements directly from an IRA without increasing adjusted gross income. The 2026 QCD limit is $111,000 per IRA owner age 70½ or older, with a one-time split-interest QCD limit of $55,000. While the dollar amounts are capped, QCDs are exceptionally valuable under the new rules because they are excluded from income entirely, completely avoiding both the 0.5 percent floor and the 35 percent deduction cap. Note, however, that QCDs cannot be directed to a DAF or private foundation.

For estate and wealth planning, the 2026 annual gift tax exclusion remains set at $19,000 per recipient, meaning a married couple splitting gifts can transfer up to $38,000 per individual without incurring gift taxes or eating into lifetime limits. The federal lifetime estate and gift tax exemption stands at $15 million per individual, or $30 million for a married couple via portability or proper planning. Utilizing these exclusions before December 31 allows families to transfer assets and shield future asset appreciation from taxation.

Small business owners and self-employed individuals should pay special attention to year-end equipment purchases, state tax workarounds and depreciation rules. Expensing provisions under tax regulations allow businesses to deduct the full cost of qualifying equipment and software purchased and placed in service before the end of the year, providing a strong incentive to upgrade technology, machinery or infrastructure while lowering business taxable income. Crucially, the Pass-Through Entity (PTET) election survived OBBBA and is arguably more vital than ever, as high-income owners with a MAGI above approximately $606,000 are subject once again to a strict $10,000 SALT cap. Business owners must coordinate these PTE taxes where applicable to mitigate the federal cap on state and local tax deductions. Readers should be reminded that many states require the election and actual payment to be made by December 31 to secure a 2026 federal deduction, making this a critical year-end action item. Structuring owner compensation, evaluating qualified business income deductions and reviewing entity classifications with a qualified tax professional ensure that business structures remain optimized for tax efficiency.

Looking Ahead: 2027 Planning Considerations
While finalizing 2026 actions is the immediate priority, taxpayers should also maintain visibility into 2027. The sweeping provisions established by OBBBA, including the new charitable floors and deduction caps, will largely carry forward, meaning there is little cross-year rate arbitrage opportunity on deductions. However, key thresholds will undergo inflation adjustments, and strategic planning will require transitioning to the permanent Opportunity Zone rules taking effect in 2027, adapting to Roth catch-up mandates, and continually assessing state-level PTET workarounds.

Finally, proper management of estimated tax payments, comprehensive recordkeeping and professional consultation are important components of a successful tax strategy. Taxpayers should review their year-to-date withholdings and quarterly estimated payments against the safe harbor rules, paying at least 90 percent of the current year’s tax liability or 110 percent of the prior year’s liability, to avoid unexpected underpayment penalties in April. Tax laws are intricate and subject to legislative changes, making it important to stay informed about current 2026 thresholds, phase-outs and credit availability. Maintaining organized records of receipts, donation acknowledgments, investment transactions and business expenses simplifies the preparation process and ensures that all legitimate claims are substantiated.

Your Oxford team brings deep experience working with families and business owners on their overall planning goals and objectives. In coordination with your legal and tax advisors, we apply thoughtful, customized strategies to help ensure peace of mind and financial optimization as the year concludes.

Oxford Financial Group, Ltd. (“Oxford”) is a Registered Investment Advisor (“RIA”) with the U.S. Securities and Exchange Commission (“SEC”) and is headquartered in Carmel, Indiana. Registration with the SEC does not imply a certain level of skill or training. Additional information about Oxford, including our Form ADV and Privacy Policy, is available upon request by calling 800.722.2289 or emailing info@ofgltd.com. The content of this presentation is intended for educational and illustrative purposes only. It should not be construed as investment, tax, or legal advice, nor as a recommendation or offer to buy or sell any security or investment product. The strategies referenced above are illustrative in nature and may not be available, suitable or advisable for every individual, entity or transaction. No strategy discussed guarantees the achievement of any tax, estate planning or transaction objective. Investing involves risk, including possible loss of principal. Tax and legal counsel should be engaged before taking any action. This material has been prepared using original sources believed to be reliable, but no representation is made as to its accuracy or completeness. The views expressed are those of Oxford as of the date of the presentation and are subject to change based on market, regulatory or economic conditions, which may not occur as anticipated. For full disclosures and disclaimers, please visit https://ofgltd.com/home/disclaimers. OFG-2610-33

The Opportunity Zone Bridge: Navigating the 2026 Tax Transition, Capital Lock-Up and the Architecture of OZ 2.0

For nearly a decade, the Qualified Opportunity Zone (QOZ) program lived under a statutory deadline. Enacted under the Tax Cuts and Jobs Act of 2017, it required investors to recognize all deferred capital gains no later than December 31, 2026. That deadline is why late 2026 has become such an active planning season for family offices holding legacy Qualified Opportunity Fund (QOF) positions.

At its simplest, a Qualified Opportunity Zone (QOZ) is a designated low-income census tract that Congress wants to see more private investment reach. A Qualified Opportunity Fund (QOF) is the vehicle that gets capital there. It pools eligible capital gains from investors, and in exchange for deploying that money into qualifying property or businesses inside a QOZ, it offers deferral and eventual reduction of the tax on those gains.

The One, Big, Beautiful Bill Act of 2025 (OBBBA) changed the underlying premise. Section 70421 made the Opportunity Zone program permanent, and IRS Notice 2026-40, transitional guidance from the Treasury Department and the IRS, supplies the rules connecting the expiring legacy regime (“OZ 1.0”) to the new permanent framework (“OZ 2.0”). Together they turn what was once a temporary incentive into a recurring feature of the tax code, complete with its own mechanics, its own deadlines and, since this is still a ten-year illiquid commitment, its own opportunity cost.

We will walk through what changed in the transition and what stayed the same, then turn to the question most relevant to Qualified Opportunity Zones: Does the tax benefit outweigh the investment risk, illiquidity, fees and opportunity cost that come with it?

Notice 2026-40 and the Permanent OZ 2.0 Regime

Congress originally designed Opportunity Zones under IRC §1400Z-2 as a temporary economic development tool, offering deferral of capital gains through 2026, a partial basis step-up for early investors and elimination of tax on post-acquisition appreciation after a 10-year hold. Section 70421 of the OBBBA converted that temporary structure into a permanent one. Under OZ 2.0, state governors will nominate low-income census tracts for recurring 10-year designation cycles, with the first cycle running from January 1, 2027 through December 31, 2036.1

Notice 2026-40, a piece of transitional guidance issued by Treasury and the IRS rather than a statute in its own right, resolves several open questions in bridging the two regimes. Chief among them is the statutory cap limiting designated zones to 25% of a state’s low-income communities “during any period” under §1400Z-1(d)(1). Because legacy OZ 1.0 tracts remain designated through December 31, 2028, some advisors worried the overlap would shrink the number of new tracts available for OZ 2.0. The Notice clarifies that the 25% cap applies independently to each 10-year designation period, so existing OZ 1.0 tracts do not reduce the inventory available for new OZ 2.0 nominations.2

Rev. Proc. 2026-14 sets the nomination calendar. State chief executives were able to submit and revise OZ 2.0 nominations from July 1, 2026 through September 28, 2026, with a single 30-day extension available on request. Treasury and the IRS identified 25,332 eligible census tracts nationwide, of which 8,334 are composed entirely of a rural area and qualify as Rural Opportunity Zones.3

The distinction matters for planning. Capital invested through a Qualified Rural Opportunity Fund (QROF) in one of these tracts could receive as much as a 30% basis step-up at the five-year mark, three times the 10% standard step-up available elsewhere under OZ 2.0, reflecting Congress’s intent to direct more of the permanent incentive toward non-metropolitan communities.4

An OZ 1.0 tract does not automatically carry forward into the new regime, a detail that catches many clients by surprise. Each tract must independently satisfy OZ 2.0’s tightened eligibility test and receive its own nomination and designation, and new capital deployed into a tract that is not renominated will not qualify for OZ 2.0 treatment.5

A key point to note is that many states and localities apply their own conformity rules, and some run separate opportunity zone-style programs of their own, so confirming state treatment before relying on any after-tax projection is a reasonable starting point.

OZ 2.0 Versus OZ 1.0: What Actually Changes

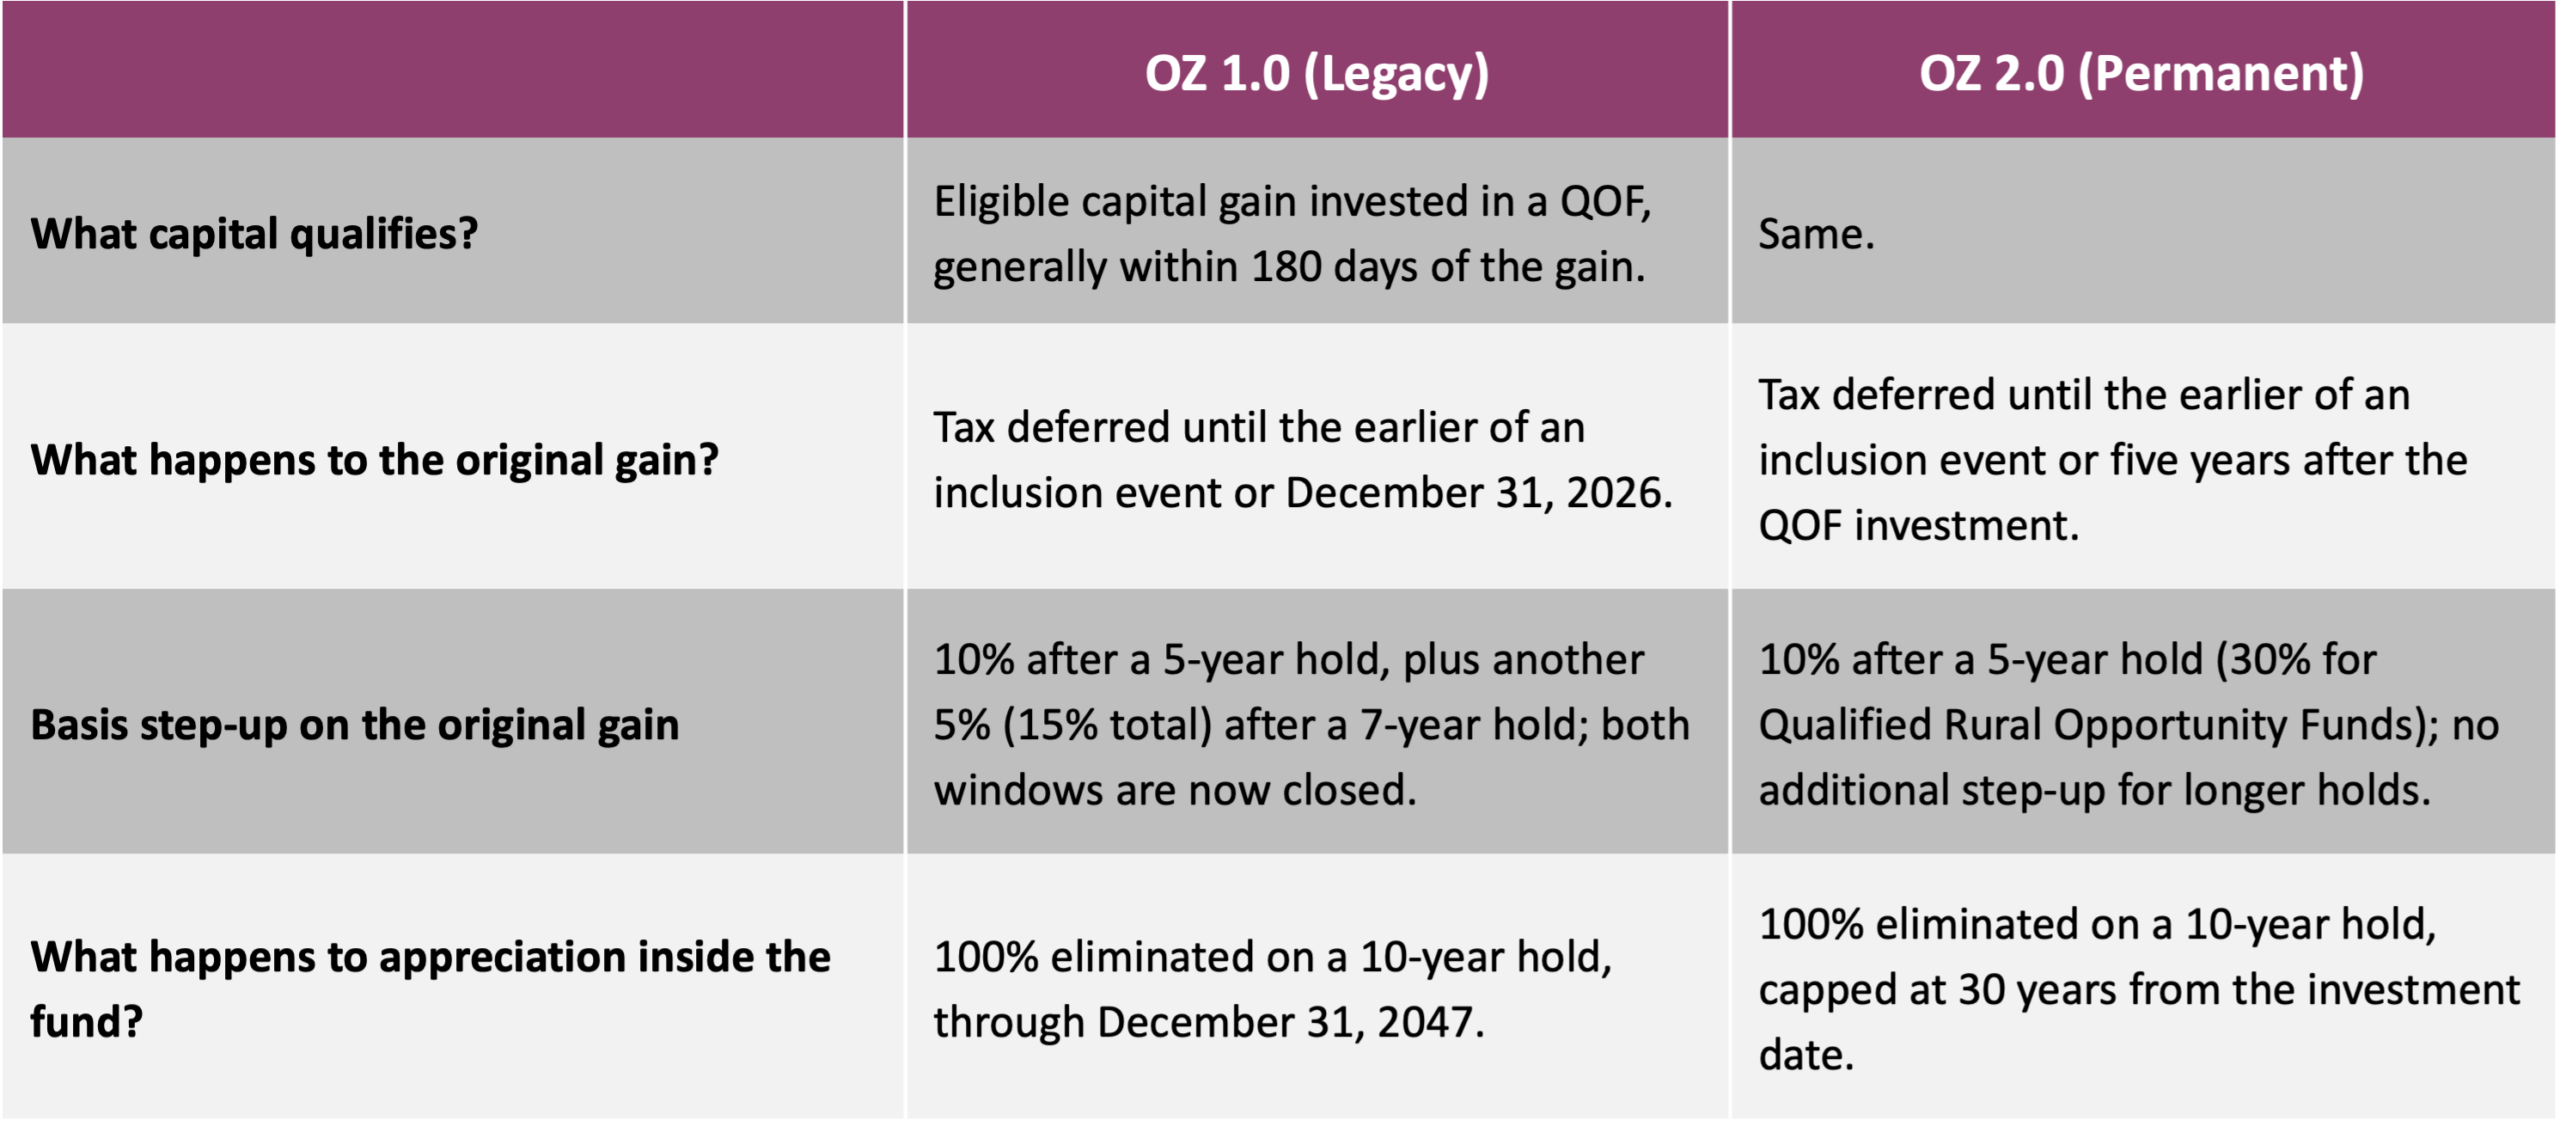
The permanent regime changes more than the sunset date. The mechanics are easiest to follow once you separate the two tax incentives at work here, deferral on the original capital gain and elimination of tax on the fund’s own appreciation, since conflating them is the most common source of confusion.6

The Deemed Inclusion Event

Two mechanics deserve a closer look because they affect every legacy investor regardless of new deployment plans. Under Section 4.01 of Notice 2026-40, every legacy QOF investment still held as of December 31, 2026 must recognize its remaining deferred gain on the 2026 return, payable in spring 2027. That gain cannot be re-deferred into a new fund; the original deferral election remains in effect, so the recognized amount is not treated as new eligible gain. The taxable amount is the original deferred gain, reduced by any basis step-up already earned under the 5- or 7-year holding rules above. It is further capped at the investment’s fair market value on December 31, 2026 if that value is lower, which is why a rigorous, independent valuation matters in any sector where values have softened. Paying this tax does not end the benefit. An investor who keeps the QOF interest for a full 10 years may still qualify for the step-up to fair market value on disposition under §1400Z-2(c), through December 31, 2047 for legacy assets.7

The Safe Harbor for Legacy Developers

Tangible property acquired after December 31, 2026 in an OZ 1.0 tract will generally fail to qualify as Qualified Opportunity Zone Business Property unless it fits one of two exceptions under Section 5.01: a written working capital plan (up to 31 months) adopted by December 31, 2026, with at least 10% of capital received and 5% expended or committed by that date, or an ordinary-course replacement of existing assets, such as routine renovations, that does not expand the project’s footprint or scope.8

For new capital, the practical difference comes down to timing. Gain deployed into a QOF on or before December 31, 2026 falls under OZ 1.0 and offers no step-up, and deferral only through December 31, 2026; the same gain, deployed on or after January 1, 2027, starts a fresh five-year deferral clock and a 10% (or 30% for Qualified Rural Opportunity Funds) basis step-up under OZ 2.0.

Evaluating the Opportunity Cost of Capital Lock-up

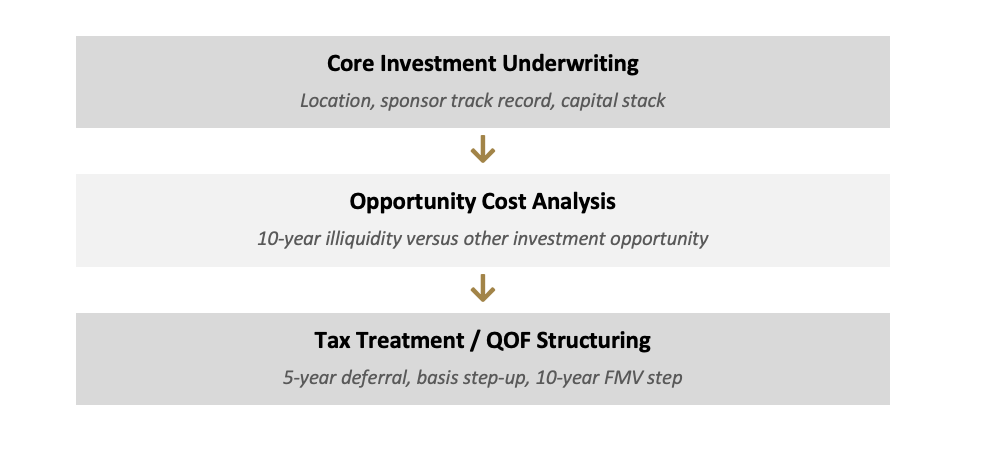
Tax incentives are only half of the underwriting question. Sound family office governance calls for weighing that benefit against what the capital would otherwise earn, and against how long it will be committed.

The 10-Year Illiquidity Premium

Whether under OZ 1.0 or OZ 2.0, the core benefit, elimination of tax on appreciation under §1400Z-2(c), requires a minimum 10-year hold, and up to 30 years under the new statutory cap. In a zero-rate environment, locking up capital for a decade was a low-cost trade. In a higher-for-longer environment where core fixed income, private markets and public equities may offer competitive after-tax returns on their own, that same lock-up now carries a genuine cost, in the form of reduced ability to rebalance through a market dislocation and, for ground-up projects, added exposure to development, supply chain and refinancing risk over a long horizon.

The Phantom Tax Cash Drag

Legacy investors face a distinct liquidity event in spring 2027. The tax bill on the 2026 deemed inclusion gain comes due in outside cash, while the underlying asset may still be years from stabilization. Sponsors that once expected to fund these liabilities through cash-out refinancings now face a tighter debt market, which shifts more of that burden onto the family office’s own balance sheet.

Sponsor and Fee Scrutiny

A QOF deserves the same underwriting rigor as any private equity commitment. Acquisition fees, professional fees and other costs can erode the after-tax benefit the code is designed to provide. The underlying investment can still lose money like any illiquid real asset, and tax benefits can be forfeited through noncompliance, independent of investment performance, if a QOF or QOZB fails to meet asset-testing or certification requirements.

What the Data Actually Shows

An August 2026 Government Accountability Office (GAO) review put total Opportunity Fund assets at roughly $108 billion at the end of 2024, concentrated in urban multifamily housing, mixed-use development and hotels. GAO found, echoing a similar finding in its 2020 review, that no centralized data exists on which projects are funded, and that investment has skewed toward tracts that already had infrastructure and community support in place, rather than the most economically distressed communities the program was designed to reach. The earliest QOF investments were made in 2018 and 2019, however, so the first cohort of full 10-year holds is only now maturing. Even a complete data set today would say relatively little about realized, full-cycle outcomes, since most of the program’s history to date has been the accumulation phase rather than the exit phase.9

OZ 2.0 takes a meaningful step toward closing this gap. The permanent regime requires QOFs to report fund and investor characteristics annually, with Treasury due to publish outcome data by the program’s sixth year. As that reporting accumulates, investors and their advisors should be better positioned to judge whether realized returns justify the illiquidity, fees and opportunity cost described throughout this piece, rather than relying on the tax mechanics alone. None of this diminishes the tax benefits available today, but it does argue for underwriting the underlying investment on its own merits.10

Estate and Trust Considerations

An Opportunity Zone position raises estate and trust questions best surfaced well before a liquidity event forces the issue. What happens to a QOF interest at death, including how it is valued and whether the fund’s own operating agreement restricts transfer, deserves the same attention as any other illiquid asset in an estate plan. Lifetime gifting of a QOF interest raises its own question about whether the transfer itself triggers an inclusion event. And for a trust considering a QOF allocation, the illiquidity described above deserves a hard look against the trust’s distribution obligations to beneficiaries. These are highly fact-specific questions, best worked through with counsel alongside the family’s broader estate plan.

Conclusion

Notice 2026-40 accomplishes what it set out to do: it gives legacy investors, developers and fund sponsors a workable bridge from a temporary incentive to a permanent one, with transitional guidance for the 2026 transition and a durable framework beyond it. That clarity is valuable, but it answers a different question than whether a given Opportunity Zone investment is the right long-term financial play for a portfolio.

The permanence of OZ 2.0 means this decision will keep coming up, for existing legacy positions working through the 2026 transition and for new capital weighing deployment into the years ahead. Families and their advisors are likely best served by treating the tax benefit as one input among several, alongside the underlying investment’s own merits, its illiquidity, its estate and trust implications and the still-thin record of how prior-generation Opportunity Zone investments have actually performed. How much weight each family gives those factors is, appropriately, a complex equation that needs to be an ongoing consideration.

One related structure we get asked about often is the two-layer strategy of operating a Qualified Opportunity Zone Business directly within a QOF. It carries its own operating, financing and exit considerations beyond the scope of this piece, and we plan to address it, along with the risks specific to it, in a follow-up article.

Clients with questions about how this topic may relate to their own circumstances are encouraged to speak with their Oxford advisory team and their tax and legal advisors.

Oxford Financial Group, Ltd. (“Oxford”) is a Registered Investment Advisor (“RIA”) with the U.S. Securities and Exchange Commission (“SEC”) and is headquartered in Carmel, Indiana. Registration with the SEC does not imply a certain level of skill or training. Additional information about Oxford, including our Form ADV and Privacy Policy, is available upon request by calling 800.722.2289 or emailing info@ofgltd.com. The content of this presentation is intended for educational and illustrative purposes only. It should not be construed as investment, tax or legal advice, nor as a recommendation or offer to buy or sell any security or investment product. The strategies referenced above are illustrative in nature and may not be available, suitable or advisable for every individual, entity or transaction. No strategy discussed guarantees the achievement of any tax, estate planning or transaction objective. Investing involves risk, including possible loss of principal. Investing involves risk, including possible loss of principal. Tax and legal counsel should be engaged before taking any action. This material has been prepared using original sources believed to be reliable, but no representation is made as to its accuracy or completeness. The views expressed are those of Oxford as of the date of the presentation and are subject to change based on market, regulatory or economic conditions, which may not occur as anticipated. For full disclosures and disclaimers, please visit https://ofgltd.com/home/disclaimers. OFG-2610-05

1 One, Big, Beautiful Bill Act, Pub. L. No. 119-21, § 70421 (2025), amending IRC § 1400Z-1(f)(1).
2 IRC § 1400Z-1(d)(1); IRS Notice 2026-40, § 3.01(1) (June 18, 2026).
3 Rev. Proc. 2026-14 (IRS, Apr. 6, 2026).
4 IRC § 1400Z-2(b)(2)(B)–(C), as amended by One, Big, Beautiful Bill Act, Pub. L. No. 119-21, § 70421 (2025).
5 Rev. Proc. 2026-14 (IRS, Apr. 6, 2026).
6 IRC §§ 1400Z-2(a)–(c), as amended by One, Big, Beautiful Bill Act, Pub. L. No. 119-21, § 70421 (2025); IRS Notice 2026-40, §§ 4.01, 5.01–5.02 (June 18, 2026).
7 IRS Notice 2026-40, § 4.01 (June 18, 2026); IRC § 1400Z-2(a), (c).
8 IRS Notice 2026-40, § 5.01(2)–(3) (June 18, 2026).
9 U.S. Government Accountability Office, GAO-26-108132, Opportunity Zones: Effects of Original Tax Incentive Mostly Unknown and Revised Incentive May Offer Improvements (Aug. 24, 2026).
10 REG-116506-25, 91 Fed. Reg. 57968 (proposed Sept. 11, 2026).

Third Quarter 2026 Review: A Cut Deferred, a Hike Delivered

The third quarter opened with the Federal Reserve’s first expected rate cut sliding further into 2027 and an economy warming at the top line while the workers inside it felt none of it. It closed with a unanimous quarter-point increase, crude near $110 a barrel and consumer confidence at its lowest level since April 2014. In 90 days the governing question moved from when the easing would begin to how many increases the year still holds.

The deeper story was about a central bank that stopped looking through supply shocks. Three of them overlapped through the quarter: an energy crunch that reopened in July and worsened in September, an artificial intelligence (AI) buildout that lifts investment and imports in nearly equal measure and the residue of tariffs. For most of the past two years the committee treated disturbances of this kind as noise to see past. By the end of September, it had decided otherwise, and the decisive input was not a wage number or an output gap but a damaged pipeline in Saudi Arabia. The quarter also closed with a set of annual revisions that made the recent past look better in almost every respect and changed the path ahead not at all.

Executive Summary

  • Rates are on the rise. The Federal Open Market Committee (FOMC) held the policy rate at 3.5% to 3.75% in July on a 9-to-3 vote, with three regional Federal Reserve presidents dissenting in favor of an increase, then raised the rate 25 basis points to a range of 3.75% to 4% in September, unanimously, with the projections pointing to risk management rather than overheating as the motive.
  • Energy struck twice. The collapse of the United States-Iran truce reclosed the Strait of Hormuz in July and pointed retail gasoline back toward $4.50 a gallon, and September damage to Saudi Arabia’s East-West pipeline, the critical alternate route for Middle East crude, sent oil close to $110 a barrel. Diesel became the most consequential price in the economy at $6.50 a gallon, a level consistent with crude at $156, with tightness in refined products capable of adding as much as four tenths of a point to core inflation next year.
  • The labor market maintained its equilibrium. The labor market stopped hiring without starting to fire. Nonfarm payrolls fell 23,000 in July before rising 162,000 in August, while the layoff rate slipped to 1.0% and the hiring rate held near 3.3%.
  • Annual inflation revisions rewrote the recent past favorably. Core Personal Consumption Expenditures (PCE) inflation now runs at 3% rather than the pre-revision 3.3%, growth in 2024 and 2025 came in two tenths higher with most of the gain in AI-exposed categories, and the personal saving rate moved up by more than 1.5 points to above 4%.
  • The consumer maintained its split personality. Households spent well and felt terrible. Confidence fell to 81.9, its weakest since April 2014, sentiment finished the quarter at 48.1 with year-ahead inflation expectations at 4.6% and the third quarter nowcast for consumption still ran at 3.3% annualized.
  • AI giveth and taketh away. The AI buildout kept adding to activity and subtracting from measured output, with capital goods imports up 57.2% over the year and net trade on track for a 3-percentage point drag on third-quarter growth, the largest since the first quarter of 2025.

The Fed: From Waiting to Hiking
No institution traveled further this quarter than the Federal Reserve, and it traveled in the direction nobody had penciled in. July opened with the first expected cut sliding toward the back half of 2027, pushed there not by a cracking economy but by a steady one that gave the committee no reason to hurry. At the July 29 meeting the committee held at 3.5% to 3.75%, and the vote told the more interesting story: 9 to 3, with three regional Federal Reserve presidents dissenting in favor of an increase, against market pricing of roughly a one-in-three chance of a hike, which sent Treasury yields sharply lower once the decision landed. A committee that argues loudly and then leaves the thermostat alone is still a committee that has moved, if only in temperament.

Jackson Hole was the hinge. Chair Kevin Warsh used his keynote to reaffirm 2% inflation on the PCE measure as a firm, fixed target. After months of studied ambiguity, the implication from the Chair is that policy settings were not restrictive, a departure from the language of his predecessor and from a dot plot placing the policy rate above the longer-run neutral level, and that underlying inflation was moderating too slowly. Markets did the rest, moving the September decision to a coin toss from roughly one-in-three odds and pricing two increases over the coming year. A chair who declines to give forward guidance had moved the rate path further with one speech than most predecessors had managed with a statement.

September delivered what August had implied. The committee raised the policy rate a quarter point to a range of 3.75% to 4%, unanimously, with the projections suggesting risk management rather than an overheating economy as the motive and with several participants lifting their estimate of the neutral rate, which amounts to conceding that policy had never been as tight as they supposed. Warsh defended the decision by naming three developments, and one of them was not an economic statistic at all, since alongside higher energy costs and a labor market that had stopped worrying him he cited the geopolitical flare-up in the Middle East.

The structural revision matters more than the next meeting. The path now runs to a cutting cycle spread across 2028 that arrives at a new and higher neutral rate of 3.25% to 3.5% A change that reflects stronger productivity growth, AI-driven investment demand and persistently large federal deficits that is likely to keep longer-term Treasury yields elevated on its own. Markets have run further still, pricing 90 basis points of tightening over the coming year, which Oxford Economics doubts the committee will deliver. The quarter therefore ends with the same disagreement it spent September resolving, only shifted one increase to the right.

  • Key Takeaway: The Fed spent the first half of the quarter finding reasons to wait and the second half finding reasons to move, and the trigger came from outside the domestic economy entirely. What changed durably is the level around which policy settles, since a higher neutral rate is likely to keep long yields elevated regardless of how many increases December brings.

Energy: Two Shocks in One Quarter
The energy story that Q2 closed on a note of relief reopened within days of the new quarter. The truce between the United States and Iran fell apart in early July, the Strait of Hormuz closed again and wholesale prices pointed retail gasoline back toward $4.50 a gallon after weeks of improvement. By the end of July gasoline had climbed back above $4, keeping upside risk to inflation alive at precisely the moment the committee would have preferred a quiet summer.

September brought the larger blow, and it arrived from infrastructure rather than diplomacy. Damage to the East-West pipeline in Saudi Arabia, which had served as the critical alternate path for Middle East oil exports since the Strait closed, pushed crude close to $110 a barrel and looked to keep prices higher for longer. This had economists reworking their baseline forecasts, lifting West Texas Intermediate forecasts to an average above $100 a barrel in the fourth quarter against $80 previously. A single length of pipe moved the oil forecast by more than twenty dollars a barrel, which is a useful reminder of how little of the macro outlook the macro data actually contain.

The most dangerous price was not crude but diesel. It reached $6.50 a gallon, a level consistent with an oil price of $156 a barrel, a gap that speaks to an extraordinary refining spread and that will persist while tanker traffic through the Strait runs far below normal. Diesel matters more than gasoline for the inflation outlook because it sits inside the cost of producing and shipping ordinary goods and feeds directly into grocery, restaurant and delivery prices. Tightness in refined products could add as much as four tenths of a percentage point to core inflation next year. The proposed remedy carries its own hazard, since a ban on diesel exports would lower prices on the Gulf Coast and in the Midwest while raising them in the Northeast and on the West Coast, and would risk cutting refinery output and lifting gasoline prices. Hopefully, the measure is unlikely to occur.

The forecast arithmetic followed directly. The revised baseline carries headline Consumer Price Index (CPI) inflation as much as four tenths higher and nudges core CPI up a tenth, with food inflation now peaking later in 2027 and the additional energy passthrough to core prices running mainly through non-energy consumer goods and airfares. Firmer prices arrive paired with slightly slower growth, at 2.1% this year and 2.4% next, each a tenth below the estimate at the start of September.

  • Key Takeaway: The quarter contained two separate energy shocks, one diplomatic and one physical, and the second proved worse than the first. Diesel is the variable that carries the shock into everything else, and it is the reason a supply disruption half a world away now shows up in a domestic policy rate.

Inflation: The Round Trip That Did Not Finish
Inflation spent the quarter looking as though it had turned the corner, right up until it did not. June brought a benign reading, with headline CPI falling 0.4% and the annual rate dropping to 3.5% from 4.2% while core prices came in flat, showing little of the tariff or AI passthrough the committee had watched for. July was nearly as kind, with headline CPI up 0.1% and core up 0.2%, leaving core running at 2.5% over the year. Two months of that sort of data is the stuff of which patience is made.

August ended it. Core CPI surprised to the upside at 0.3% with headline CPI up 0.4%, and the strength sat in non-housing core services, the category the Fed watches most closely because it reflects domestic demand rather than imported costs. Airfares, motor vehicle maintenance and repair, lodging away from home and wireless telephone services all accelerated together, which is the pattern energy costs leave behind when they stop being an energy story and become a services story.

Then the statisticians intervened. The Bureau of Economic Analysis (BEA) annual update of the national accounts revised measured core PCE inflation down by roughly three tenths, leaving it at 3% rather than the pre-revision 3.3%, on methodological improvements to three contested categories: computer software and accessories, portfolio management and legal services. The bulk of the improvement sat in portfolio management and investment advice fees, which rise and fall with stock prices and which Fed officials had already discounted in favor of the market-based PCE index. Getting a better thermometer is genuinely useful. It does not make the room any cooler.

Which is why the revision changed the record without changing the outlook. Core inflation still sits well above target with risks stacked firmly to the upside because of refined petroleum prices, and higher energy prices is projected to keep inflation tracking above 3% through the first quarter of 2027. The quarter thus ends with the curious result that inflation was lower than everyone believed and the Fed tightened anyway, which is what happens when a central bank starts managing the distribution of outcomes rather than the central case.

  • Key Takeaway: Two benign months gave way to a firm August and then to revisions that lowered the entire recent history of core inflation. None of that resolved the underlying problem, since the level remains too high and the energy passthrough still ahead of us points in one direction only.

The Labor Market: The Expansion That Forgot to Hire
The labor market spent the quarter delivering the same message in progressively stranger ways. July payrolls fell 23,000 against a forecast gain of 80,000, though a 50,000 drop in state and local government employment accounted for the entire decline while private payrolls still rose 30,000. August then produced 162,000 against a consensus of 55,000, with July’s reported decline flipping to a 21,000 gain and the three-month average climbing to 71,000. Two months, two opposite headlines, one unchanged trend.

The reason those headlines meant so little is that the yardstick kept shrinking. A dwindling pool of available workers dragged the breakeven pace of hiring, the monthly job growth needed to hold the unemployment rate flat, toward 20,000 in the second half of the year, low enough that a negative print carries almost no information. The preliminary annual benchmark revision then trimmed 79,000 from the March level of payrolls, a rounding error beside the 861,000 final revision for 2025, and in nine of the past ten years the final revision has landed more positive than the preliminary estimate. Measuring this labor market against a fixed standard is like weighing yourself on a scale that recalibrates each morning.

The mechanism underneath deserves more attention than it received. This year’s improvement ran almost entirely through falling layoffs rather than rising hiring, with the layoff rate slipping to 1.0% in August from 1.1% while the hiring rate managed only 3.3% from 3.2%, inside the depressed 3.1% to 3.5% band of the past two years. The quits rate held at 1.9%, which is what workers do when they doubt they could find something better. Claims confirmed the calm, touching 187,000 in July, the lowest level since 1969, a figure that predates the microprocessor, and September closed with private payrolls in the Automatic Data Processing (ADP) report up 90,000 while the three-month average held at 57,000, close to breakeven. With layoffs already at historic lows, any further warming has to come from hiring, and hiring is the part that energy costs and tighter credit reach first.

For policy, the wage numbers mattered more than the payroll numbers, and they cooled all quarter. Average hourly earnings growth eased to 3.1% over the year while the Oxford Economics wage tracker fell below 3% for the first time in five years. Slower labor force growth is projected to hold the unemployment rate near 4.2% through 2027, which leaves the labor market as the one part of the inflation debate that never became an argument.

  • Key Takeaway: The quarter produced a negative payroll month, a strong one and a downward benchmark revision, and none of the three changed the picture of a market balanced at a very low level of churn. Labor never threatened the inflation outlook, which is precisely why the shocks that did came from outside it.

The Consumer and Housing: Stronger on Paper, Sourer in Practice
Households spent the quarter behaving better than they felt, and the gap between the two widened every month. Second-quarter consumption grew a resilient 3.2% annualized on the advance estimate, trimmed later to 2.9%, July retail sales dropped 0.6% on seasonal distortion around a shifted online shopping event and August recovered with a 1.2% gain led by discretionary categories. By quarter-end, after revisions, the third quarter nowcast for consumption ran at a 3.3% annualized pace against 2.8% previously.

The revisions improved the foundation as well as the flow. The personal saving rate moved up by more than 1.5 points to above 4%, meaning households entered the energy shock with a materially larger cushion than anyone had credited them with, and gross domestic income came in higher on new and much larger estimates of net interest income, which leaves recent spending resting on firmer ground than the pre-revision data implied.

None of which the consumers noticed. The University of Michigan sentiment index finished September at 48.1, with the expectations component down 10% for its largest decline since April 2025, and year-ahead inflation expectations jumped six tenths to 4.6%, above the 3.4% level that prevailed before the war. The Conference Board measure fell to 81.9 from 88.6, the weakest reading since April 2014, when the index was still climbing out of the Great Recession. Its labor differential, the gap between those calling jobs plentiful and those calling them hard to get, dropped 2.5 points to 1.7, the lowest since February 2021, which says less about layoffs than about how it feels to look for work when nobody is hiring.

Housing was the clearest casualty of the rate path. Mortgage rates climbed more than 30 basis points over the final month toward 7%, homebuilder sentiment fell three points to 32 on deteriorating current and expected sales and existing home sales slipped 2% in August to 3.98 million, down 1.2% from a year earlier. Prices offered a last piece of good news that reads like a peak, with the national index up 1.9% over the year in July, the largest annual gain since June 2025, though favorable base effects have now passed and the 2027 price forecast is due for a markdown, since rates above 7% price buyers out even as they keep sellers on the sidelines.

  • Key Takeaway: The revisions made the household balance sheet look considerably better, and confidence fell to a twelve-year low anyway. Spending is carried by the households that own assets, while the households that buy gasoline set the tone of the surveys and housing absorbs the full cost of a rate path neither group chose.

The AI Economy: Adding More, Netting Less
The through-line of the quarter, as of the two before it, was artificial intelligence. Core capital goods orders rose 1.6% in August on solid gains across primary metals, machinery and electrical equipment, keeping the forecast for equipment spending to expand 10.7% in 2026, the strongest annual pace in more than a decade. Corporate profit margins sit at all-time highs, business inventories remain lean and the tailwind from AI keeps broadening from information-processing equipment into machinery and metals, which is why higher financing costs have not yet bitten.

The same buildout keeps punishing the trade account. The advance goods deficit widened $13.7 billion to $132.6 billion in August, the largest since the first quarter of 2025, as imports climbed 5.5% against a 1.9% rise in exports, putting net trade on track to subtract 3 percentage points from third-quarter growth. Capital goods imports now stand 57.2% above year-ago levels, and the strength has begun to broaden, with all other imports up 11.8% over the year, their fastest since March 2025. A country that buys the hardware abroad and books the spending at home may continue to see the two largely cancel.

The annual revisions finally gave the buildout some statistical credit. Growth in 2024 and 2025 came in two tenths higher, with most of the revision in business fixed investment and roughly two thirds of that concentrated in categories sensitive to AI, including information technology equipment, research and development and data center investment. The third estimate of second-quarter output rose to 2.2% annualized from 1.5%. Taken with the downward revision to measured inflation, the message is that AI has been adding more to growth and less to prices than the data previously showed, which is close to the opposite of how the debate ran for most of the year.

The dependency is the part to keep in view. The revisions do not change the perception that the economy leans increasingly on AI gains and on the wealth effects that lift higher-income spending, which leaves it sensitive to a sudden reversal of optimism. There is a more hopeful reading available as well, since stronger measured productivity could shift the conversation from what AI does to inflation toward what it undoes, with disinflationary effects that may show up more prominently in 2027. Both readings rest on the same assumption, which is that the capital keeps flowing.

  • Key Takeaway: AI drove the investment cycle, the import surge and after revisions, a meaningful share of the growth the economy turned out to have had all along. The concentration cuts both ways, since the same force that has carried three quarters of expansion is the one whose reversal would be hardest to replace.

Final Thoughts
The third quarter of 2026 will be remembered as the quarter the Federal Reserve stopped waiting. It began with the first expected cut sliding toward the back half of 2027 and ended with a unanimous increase and another penciled in for December, and the decisive event was neither a wage spiral nor an overheating consumer but a damaged pipeline in Saudi Arabia that took crude toward $110 and diesel to a level implying $156 crude. Underneath the policy drama the economy performed better than it felt, with the labor market balanced at a very low level of churn, wage growth below 3% and annual revisions that raised past growth, lowered measured core inflation to 3% and lifted the saving rate above 4%. The unfinished business is the energy passthrough still working its way into core prices, a consumer whose confidence sits at a twelve-year low while spending holds and an expansion that depends on an AI capital cycle it could not easily replace. The fourth quarter will test whether a central bank that has learned to react can avoid overcorrecting for a disruption that monetary policy was never able to fix, and whether an economy that has absorbed three shocks in nine months has any absorption left.

Oxford Financial Group, Ltd. is a SEC-registered investment adviser. Registration does not imply a certain level of skill or training. The information provided is for general informational purposes only and should not be considered investment, tax or legal advice. Opinions are those of the author and are subject to change based on market, regulatory or economic conditions. Forward-looking statements are opinions and/or estimates and are not guarantees of future results. Data and opinions are based on sources believed to be reliable, including unaffiliated third parties such as Oxford Economics, but their accuracy cannot be guaranteed. Past performance is not indicative of future results. See important disclosures and disclaimers at https://ofgltd.com/home/disclaimers. OFG-2610-07

CIO Macro Trends: Diesel Sets the Rate

The last letter called the September meeting a coin toss and declined to flip it. The committee flipped it, unanimously, with a quarter-point hike delivered less because the economy was overheating than because a damaged pipeline in Saudi Arabia had made the inflation outlook unrecognizable. What followed over the next ten days was a wholesale revision of nearly every forecast that mattered, and a central bank that now sets policy with one eye on the Strait of Hormuz.

Executive Summary

  • The Federal Open Market Committee (FOMC) voted unanimously to raise the policy rate 25 basis points to a range of 3.75% to 4%, with the accompanying projections suggesting risk management rather than overheating as the motive.
  • Damage to the East-West pipeline in Saudi Arabia, the critical alternate route for Middle East crude since the Strait of Hormuz closed, sent oil close to $110 a barrel, and forecasters now look for West Texas Intermediate to average over $100 per barrel in the fourth quarter against $80 in the first September baseline.
  • Diesel at $6.50 a gallon implies an oil price of $156 a barrel, and tightness in refined products could add as much as four tenths of a point to annual core Personal Consumption Expenditures (PCE) inflation in early 2027.
  • The revised baseline carries headline Consumer Price Index (CPI) inflation up to four tenths higher with core CPI a tenth higher, and projected to trim real growth to 2.1% this year and 2.4% next, each a tenth lower than at the start of the month.
  • Third-quarter growth is tracking just under 4% annualized, with inventories alone contributing 1.8 percentage points and equipment spending another 0.9 point.
  • Consumer sentiment fell to 48.1 in September from 51.7, with the expectations component down 10%, its largest decline since April 2025, while year-ahead inflation expectations jumped six tenths to 4.6%.
  • Mortgage rates have climbed more than 30 basis points over the prior month toward 7%, and homebuilder sentiment fell three points to 32, further below the line that separates healthy conditions from poor ones.

The Fed: A Hike, and a New Reaction Function

The committee raised rates by a quarter point to a range of 3.75% to 4%, and the vote was unanimous. The accompanying projections pointed to risk management rather than an overheating economy as the motive. The proximate causes were the hotter August inflation readings and the continued climb in energy prices, which together skewed the risks toward inflation staying higher for longer, helped along by an economy resilient enough that participants lowered their unemployment projections. Several participants also raised their estimate of the neutral rate, which amounts to conceding that policy had not been as tight as they had supposed.

Chair Kevin Warsh defended the decision by naming three developments, and one of them was not an economic statistic at all: higher energy costs, a labor market that has stopped worrying him and the geopolitical flare-up in the Middle East. He again declined to offer forward guidance, though the Summary of Economic Projections said plenty on his behalf, showing almost all officials placing the risks to inflation to the upside and the risks to unemployment broadly balanced, the most hawkish arrangement in some time. A chair who refuses to tell markets what he will do has now told them something more useful, which is what he is watching. The September move will not stand alone. The second release of the September baseline pencils in another increase in December followed by an extended pause through next year, even as markets price more tightening than the committee itself projects.

The deeper change concerns how the Fed decides anything. In a world prone to adverse supply shocks, central banks will grow steadily more reactive to geopolitical stress that can unsettle inflation expectations, and the committee now appears to be done arguing over whether to look through an oil or tariff shock the way it historically would. Iran is not the only pressure point. President Donald Trump hosted Chinese leader Xi Jinping in Washington, with attention on any shift in rhetoric over Taiwan, where a genuine confrontation would amount to a global supply shock and send electronics prices higher with spillovers across the rest of the basket. Monetary policy has always responded to events. What has changed is that the events now arrive by tanker.

  • Key Takeaway: The Fed hiked because the supply side moved, not because demand overheated, and it has effectively adopted a reaction function that treats geopolitical risk as a policy input. A December increase looks likely, markets are priced for more than that and the honest position is that nobody can forecast a pipeline caught in geopolitical turmoil.

Energy: The Shock That Set the Rate

One piece of infrastructure did most of this fortnight’s work. Damage to the East-West pipeline in Saudi Arabia, which had served as the critical alternate path for Middle East oil exports since the Strait of Hormuz closed, pushed crude close to $110 a barrel and will keep prices higher for longer while delaying any disinflation in import prices. This resulted in a full reworking of the September baseline, lifting the West Texas Intermediate forecast to an average of $103 a barrel in the fourth quarter from $80, with prices also higher in 2028 and 2029 on a more persistent risk premium. Risks run both ways: (1) strikes on the Ras Tanura ports and Kharg Island would take oil toward $130 in the fourth quarter, (2) on the other hand prices have already eased somewhat as Saudi Arabia found a workaround for Asian refiners and as the prospect of faster pipeline repairs took the edge off.

The more alarming price is the one nobody quotes on television. Diesel has climbed to all-time highs, and its second-round effects worry economists more than a comparable move in gasoline, because diesel sits inside the cost of producing and shipping ordinary goods and feeds directly into grocery, restaurant and delivery prices. At $6.50 a gallon, diesel implies an oil price of $156 a barrel, a gap that speaks to an extraordinary crack spread and will persist as long as tanker traffic through the Strait stays far below normal. Tightness across refined products could add as much as four tenths of a percentage point to annual core PCE inflation by early 2027. The policy response carries its own hazard: the White House floated the notion of a 90-day ban on diesel exports, which would force refiners to cut runs and push gasoline and jet fuel higher, while risking agricultural disruption in Latin America that would return home as costlier imported food.

Import prices had already turned before the latest surge showed up in any data. They rose 0.7% in August, with nonfuel prices up 0.8% accounting for the entire increase and fuel prices down a tenth for a third consecutive monthly decline, leaving the annual rate at an elevated 7%. Buried in the detail sits a reminder that energy is not the only supply story running: computer accessories rose more than 5% on the month against a 2% decline in the August CPI, a divergence that the AI infrastructure buildout should keep alive.

The forecast arithmetic follows directly. The revised baseline carries headline CPI inflation as much as four tenths higher and nudges core CPI up a tenth, with food inflation now peaking later in 2027 and at a higher rate, and the additional energy passthrough to core prices running mainly through non-energy consumer goods and airfares. Firmer prices come paired with slightly slower growth, as real output is now expected to expand 2.1% this year and 2.4% next, each tenth below the estimate at the start of the month. There is one consolation on the measurement side. The Bureau of Economic Analysis releases annual revisions that should lower measured core PCE inflation in the second quarter by two tenths, enough to ease inflation anxiety at the central bank without erasing it.

  • Key Takeaway: A single damaged pipeline reset the oil forecast by more than twenty dollars a barrel and pulled the inflation profile up with it. Diesel is the variable to watch, since it travels into the price of nearly everything, and a proposed export ban would treat the symptom while worsening the disease.

Growth: Four Percent, Improbably

Set against all of that, the economy is having one of its better quarters. Third-quarter growth is tracking just under 4% annualized, a figure that owes more to arithmetic than to animal spirits. Headline retail sales rose 1.2% in August against an above-consensus estimate of 0.9%, with much of the strength found in a rebound in nonstore sales after the shifting timing of a major online shopping event distorted July, and with rising pump prices flattering gasoline station receipts; even allowing for that, gains were decent across most categories, led by food services, electronics and sports and recreation. Feeding that through Oxford Economics nowcast puts real consumer spending at a 2.8% annualized gain for the quarter, well above the 1.9% in the September baseline.

The second contributor is restocking. Business inventories rose 0.8% in July on strong gains in retail and wholesale, with the inventory-to-sales ratio down to 1.3 from near its decade average of 1.37 a year earlier, and the nowcast puts inventories alone at a 1.8 percentage point boost to third-quarter growth. The catch is that the energy shock attacks this channel directly, since higher transport and borrowing costs raise the expense of holding and financing unsold goods, and firms with heavy cross-border links to Canada, the automotive sector among them, now face markedly higher tariffs.

Equipment spending supplies the third leg and looks the most durable of the three. Durable goods orders held unchanged in August against a consensus decline of 0.3%, and the standout was a 1.6% rise in nondefense capital goods orders excluding aircraft, with solid gains across primary metals, machinery and electrical equipment, which keeps the forecast for equipment spending to expand 10.7% in 2026, the strongest annual pace in more than a decade. Shipments, which are what actually reach gross domestic product (GDP), slipped 0.2% and trimmed the tracking estimate for third-quarter equipment investment to a 16.1% annualized pace from 17.6%, still leaving equipment to contribute 0.9 points to growth. Corporate profit margins sit at all-time highs, and the AI buildout keeps broadening from information-processing equipment into machinery and metals, which is why higher financing costs have not yet bitten.

Factories supplied the one genuinely weak number. Industrial production held unchanged in August against a forecast gain of 0.4%, with the miss concentrated in manufacturing, which fell 0.3% and ended a seven-month run of increases. Motor vehicle assemblies fell more than 1% after seasonal adjustment, since the usual August rebound from summer retooling arrived smaller than in past years. The declines across primary metals, fabricated metals, computer and electronic products, aerospace and furniture read as the mirror image of July’s gains rather than a turn, and manufacturing output remains higher than a year ago, as it has for 15 consecutive months. Even so, the industrial production forecast loses a tenth this year and two tenths next year on higher rates and oil prices.

  • Key Takeaway: A four-handle growth quarter built on restocking, equipment and wealth-supported spending is a real achievement and a temporary one, since two of those three legs run on cheap financing and calm supply chains. Record profit margins and an AI order book give the expansion more staying power than the headlines suggest.

Housing: Seven Percent Changes Everything

Mortgage rates have risen more than 30 basis points over the prior month and now approach 7%, which is the number that governs this entire section. Builders registered it immediately. The National Association of Home Builders (NAHB) index fell three points to 32 in September against a consensus of 34, with both current and expected sales deteriorating and respondents citing mortgage rates at their highest since May 2025, rising material costs and worsening labor shortages tied to stricter immigration policy. The backlog of completed homes for sale remains near levels last seen in mid-2009, and the share of builders cutting prices rose to 38% from 35% in August.

The construction data cut both ways in a single release. Housing starts fell 2.6% to a seasonally adjusted annual rate (SAAR) of 1.275 million, yet single-family starts rose 7.6% to 918,000, their strongest pace since March, while the volatile multifamily category sank 21.7% to 357,000. An upward revision of 70,000 to July leaves third quarter starts averaging 1.29 million, a shade under the 1.3 million estimate, with the residential investment tracker pointing to an annualized decline of about 3%. Permits, the steadier guide, slipped 2.7% to 1.39 million with declines in both categories, consistent with starts running flat to lower in coming quarters. Single-family momentum, in other words, looks like a good month rather than a turn.

Sales data were better than expected and matter less than they appear. Pending home sales edged up 0.3% in August against an estimate of a 2% decline, which points to roughly flat existing sales in September, though the forecast of about 4 million sales over the balance of the year now carries an expected markdown in October, reflecting a higher oil price profile and a second-rate increase in December. New home sales rose 6.4% to 684,000, the fastest pace of 2026, with July revised up 40,000 to 643,000, and yet the nowcast for real private residential investment still sits at negative 2.82% for the quarter.

Prices tell the affordability story without editorializing. The median new home price rose 0.4% to $393,700 in August while the annual change pushed further into negative territory at 5.8%, as the mix keeps shifting down-market. Homes priced above $600,000 have fallen to 18.7% of sales and now sit below the 20.3% share taken by homes under $300,000. When the expensive tier and the cheap tier trade places, the market is not cooling so much as reorganizing itself around who can still qualify for a loan.

  • Key Takeaway: Every encouraging housing number this period arrived attached to a forecast downgrade, because rates near 7% overwhelm whatever the monthly data happen to say. Builders are discounting into a 2009-sized inventory overhang, and the sales mix is migrating toward the only buyers for which the math still works.

The Consumer, the Ballot and the Ledger

Households are spending well and feeling terrible, and the gap between those two facts keeps widening. The University of Michigan sentiment index fell to 48.1 in September from 51.7, with the damage concentrated in expectations, which plunged 10% for their largest decline since April 2025. Year-ahead inflation expectations jumped six tenths to 4.6%, their largest monthly gain in nearly six months, exceeding the 3.4% level that prevailed before the war began and fully reversing the summer’s improvement, while long-run expectations ticked up a tenth to 3.4% after three months unchanged. Headline PCE inflation now looks set to approach 4% by year end.

The spending that keeps holding up comes from a narrow place. Rising financial wealth reached a record share of household incomes in the second quarter, nearly double the share at the peak of the dot-com bubble, and most of it belongs to the top fifth of households by income, who are offsetting weakness elsewhere. Census data made the same point from the other direction: real median household income reached a record in 2025, but the top of the distribution logged a third consecutive annual increase while the bottom barely moved, and energy shocks are regressive because lower-income households spend a larger share of income on fuel.
The labor market, for its part, has gone quiet in the most reassuring way available. Initial claims fell 10,000 to 196,000 in the week ended September 12, with the four-week average at 203,250 and unadjusted claims running 22% below year-ago levels, though Labor Day timing flattered the figure, and continued claims dropped 39,000 to 1.73 million. The following week confirmed the message rather than reversing it, with initial claims down another 1,000 to 197,000 and the four-week average at 202,250. One state runs against the trend, as Hawaii saw claims rise after a category 5 hurricane, with El Nino supercharging Pacific storms. There is also a structural comfort here: research from the Boston Fed indicates the job market is far less vulnerable to energy price shocks than in prior decades. This is partly because the United States has been a net petroleum exporter since 2019, so oil-patch hiring offsets losses in importing states.

Politics and the ledger now sit closer to the macro-outlook than usual. Polling averages suggest Democrats lead in enough of the nine toss-up Senate races to take the chamber, with Texas the likely tipping-point contest, and they are expanding their generic-ballot advantage for the House. The fiscal consequences run through long yields. The baseline assumes a divided government accomplishes little beyond permanently extending the expiring tax provisions of the One Big Beautiful Bill Act (OBBBA), while upside scenarios would add one to three points to the federal debt-to-GDP ratio by fiscal 2035, and each additional point of public debt associates with a four basis point rise in the nominal 10-year Treasury yield. The war carries its own invoice, with the Congressional Budget Office (CBO) estimating that military operations in the region have cost the Pentagon about $38 billion, or 5% of its fiscal 2026 budget.

  • Key Takeaway: The consumer who owns assets is carrying aggregate spending while the consumer who buys diesel is answering surveys at levels normally associated with recessions. An inflation expectation figure at 4.6% is the number that should worry the Fed most, because it is the one input a supply shock can turn into a demand problem.

Final Thoughts

The question left open two weeks ago closed the market’s way. The Fed hiked unanimously, and it hiked for a reason that has nothing to do with the textbook, namely that a damaged pipeline made the inflation outlook worse faster than any forecaster could revise it. Everything downstream followed: oil toward $110, diesel at levels implying $156 crude, inflation expectations at 4.6%, mortgage rates near 7% and a second hike now penciled in for December.

At the same time, the economy chose this moment to post its best quarter of the year, tracking just under 4% annualized on restocking, equipment spending and the households wealthy enough to ignore the price of fuel. Growth and comfort have come apart, and a central bank that now watches shipping lanes as closely as it watches wage data is the institutional acknowledgment of that. The September jobs report and the annual national accounts revisions land in the days ahead, but the variable that decides the next few months is unlikely to appear on any economic calendar.

Oxford Financial Group, Ltd. is a SEC-registered investment adviser. Registration does not imply a certain level of skill or training. The information provided is for general informational purposes only and should not be considered investment, tax, or legal advice. Opinions are those of the author and are subject to change based on market, regulatory or economic conditions. Forward-looking statements are opinions and/or estimates and are not guarantees of future results. Data and opinions are based on sources believed to be reliable, including unaffiliated third parties such as Oxford Economics, but their accuracy cannot be guaranteed. Past performance is not indicative of future results. See important disclosures and disclaimers at https://ofgltd.com/home/disclaimers. OFG-2609-63

Oxford Welcomes Nicholas O. Detmer as Managing Director and Oxford Investment Fellow

We are pleased to announce that Nicholas O. Detmer, MBA, CFA, CAIA, has joined Oxford Financial Group, Ltd. as Managing Director and Oxford Investment Fellow® in our Indianapolis office.

Oxford’s investment platform is built around seasoned professionals with focused, institutional-grade expertise. Nick’s appointment to the Regent Street team reflects that standard, bringing a depth of private markets experience that strengthens Oxford’s capacity to source and execute on behalf of the families and institutions we serve.

Nick brings a distinguished background spanning both public and private markets. Most recently, he served as Managing Director at Aksia, where he worked as an alternatives-focused investment consultant to large institutional investors. Earlier, he spent nearly a decade at the Indiana Public Retirement System in a range of investment and leadership roles, including Deputy Chief Investment Officer, Director of Private Equity and Director of Fixed Income and Credit.

At Oxford, Nick joins a team of seasoned investment professionals focused on private markets, with responsibility for sourcing, evaluating, executing and monitoring primary fund commitments and co-investments across Oxford’s Regent Street Partners and Co-Investment funds. Nick holds a Master of Business Administration with Distinction in Finance and Entrepreneurship and Innovation from Northwestern University’s Kellogg School of Management. He earned his Bachelor of Arts in Economics with Highest Distinction from the University of North Carolina at Chapel Hill, where he was a Morehead-Cain Scholar. He is both a CFA charterholder and a Chartered Alternative Investment Analyst charterholder.


Oxford Financial Group, Ltd. is a Registered Investment Adviser registered with the U.S. Securities and Exchange Commission and is headquartered in Carmel, Indiana. Registration does not imply a certain level of skill or training. For more information about Oxford Financial Group, Ltd., or to request a copy of our Form ADV or our Privacy Policy, please call 800.722.2289 or contact us at info@ofgltd.com. OFG-2609-40

Maximizing Transaction Value Through Pre-Letter of Intent Tax Structuring

Navigating the sale of an operating company is a defining moment for founders and major shareholders. Years of operational focus finally culminate in a liquidity event. Yet, a surprising number of sellers make a critical strategic error by delaying their tax and estate planning until after a Letter of Intent (LOI) is signed. Once the ink dries on an agreement, the window for implementing the most effective wealth preservation strategies slams shut. The transaction’s economic reality is effectively set, and regulatory authorities often view subsequent planning moves through the restrictive lens of the assignment of income doctrine. To pursue more effective tax positioning, especially in transactions involving rolled equity held through a partnership structure, stakeholders must evaluate and execute pre-transaction strategies long before the formal deal parameters are finalized.

The foundational element of any equity rollover is ensuring the structure achieves the intended tax deferral. In a partnership context, this requires strict adherence to Section 721 of the Internal Revenue Code, or Section 351 depending on the entity framework. The objective is to keep the rolled portion of the equity fully tax-deferred. A common trap during this phase is the inadvertent triggering of a taxable event through what is categorized as a disguised sale under Section 707. Advisors must meticulously review the proposed flow of funds. Furthermore, auditing Section 752 debt allocations is mandatory. When a transaction results in a partner being relieved of their share of partnership liabilities, that debt relief is treated as a distribution of cash. If this hypothetical distribution exceeds the partner’s outside basis, it generates unexpected phantom income at closing. Sellers expecting a tax-free rollover can find themselves facing a substantial tax bill without the corresponding liquidity to pay it simply because pre-deal debt allocations were ignored.

Beyond the rollover mechanics, proactive stakeholders can look toward maximizing statutory tax exemptions, most notably the Qualified Small Business Stock (QSBS) exemption under Section 1202. If the operating company qualifies, early planning may be highly beneficial, though the rules have recently become bifurcated based on when the stock was issued. For QSBS issued prior to July 5, 2025, a taxpayer who meets the strict five-year holding period can generally exclude eligible gain up to the greater of $10 million or 10x their adjusted basis in the stock. However, for QSBS issued on or after July 5, 2025, the One Big Beautiful Bill Act significantly expanded these benefits. The fixed per-issuer exclusion cap was increased to $15 million, which will be indexed for inflation, while retaining the alternative 10x-basis rule. Additionally, the new law introduces a tiered holding period, allowing a 50% gain exclusion after three years, 75% after four years and a full exclusion at five years. For founders with a near-zero basis, the fixed dollar cap (whether $10 million or $15 million) is the default, but through a strategy known as stacking, this limitation can be legally multiplied. By gifting shares into multiple distinct non-grantor trusts before a deal materializes, a founder can potentially secure a separate exclusion for each trust. Timing is the crucial variable here. If these transfers occur after a LOI is signed, the transaction will likely be challenged on the basis that the right to the proceeds had already ripened and the tax liability belongs to the original owner.

Managing federal exposure is only half the equation, as state tax mitigation requires equal foresight. Depending on the seller’s state of residence and the specific tax exposure on the anticipated cash proceeds, establishing an incomplete non-grantor (ING) trust in a favorable jurisdiction like Delaware or Nevada can provide substantial relief. These structures allow sellers in high-tax states to legally shift the situs of the intangible asset before the sale, minimizing state income tax on the eventual capital gain. However, sellers in states with recent anti-ING legislation, such as California and New York, will find this is no longer an option. Alternatively, sellers must evaluate whether their existing partnership structure can make a valid Pass-Through Entity tax election regarding the transaction gain. A properly executed election can provide a workaround to the federal cap on state and local tax deductions, yielding a federal tax benefit. This requires careful financial modeling to understand the interaction between federal deduction benefits, statutory election deadlines and any complex state sourcing issues.

For sellers with philanthropic objectives, the pre-transaction period offers unique opportunities to align charitable giving with significant tax advantages. Transferring a portion of pre-transaction shares into a Charitable Remainder Trust (CRT) allows a seller to claim a partial upfront charitable deduction while retaining an annual cash flow stream. In this structure, the initial capital gain is not permanently eliminated, but it is effectively deferred and taxed over time as the seller receives the income stream. Alternatively, gifting a portion of the business interest directly to a Donor Advised Fund (DAF) provides a more immediate tax benefit. This approach yields a charitable deduction based on the fair market value of the shares and eliminates personal capital gains taxes on the future sale of that specific equity. When dealing with partnership interests, however, a critical prerequisite is verifying that the interest slated for donation does not carry a negative tax capital account. Gifting an interest with liabilities exceeding basis can inadvertently trigger a taxable event, defeating the purpose of the charitable transfer.

At the portfolio level, sellers must anticipate the character of the incoming gain and look for existing offsets. If the gain from the transaction is characterized as passive income, a comprehensive audit of the seller’s broader investment portfolio is necessary to identify any suspended passive losses. Harvesting these dormant losses to offset the influx of transaction gain is an efficient way to reduce the immediate tax burden. Understanding how basis will be treated in the deal is essential. Because partnerships maintain a single unified basis for each partner, sellers cannot cherry-pick specific high-basis tax lots to roll over while selling low-basis lots for cash. Understanding exactly how the unified basis will be allocated between the cashed-out portion and the rolled equity dictates the immediate tax reality and helps ensure the maximum possible gain is deferred. Additionally, because middle-market transactions often involve a portion of the purchase price being held in escrow for indemnification and post closing adjustments, sellers should ensure the escrow is subject to a ‘substantial restriction’ (for example, indemnity based holdbacks) to qualify for installment sale treatment. Without such restrictions, doctrines like constructive receipt or the step transaction rule can cause the escrowed funds to be taxed immediately.

While the focus is heavily weighted toward pre-deal structuring, having a definitive strategy for the post-close cash proceeds is equally vital. The tax code offers strict, time-sensitive windows for rolling cash proceeds into tax-advantaged vehicles. Sellers might consider deploying a portion of their liquidity into a Qualified Opportunity Fund, which must typically be completed within a short window following the sale. This allows for the deferral of the recognized capital gain and offers tax-free growth on the new investment if held for a decade. If the sold company was eligible for QSBS treatment but the seller had not yet met the requisite five-year holding period, they have a remarkably brief sixty-day window to execute a Section 1045 rollover. By reinvesting the proceeds into another qualifying business within two months, the seller can defer the gain and tack their holding period onto the new investment, preserving the ultimate exemption.

A comprehensive approach to transaction planning may also incorporate an overlay of estate planning. A liquidity event provides a natural valuation inflection point, making the pre-deal period an ideal time to transfer wealth to the next generation. If the timeline permits before the transaction parameters are finalized, stakeholders can evaluate utilizing vehicles like Grantor Retained Annuity Trusts (GRAT) or Intentionally Defective Grantor Trusts (IDGT). By transferring a portion of the equity at its current pre-transaction valuation, the seller locks in a lower value for gift tax purposes. When the transaction closes and the rolled equity appreciates in the new capital structure, all that future growth occurs entirely outside of the seller’s taxable estate. This shields generational wealth from estate taxes while keeping the economic upside intact.

Executing a successful business transition requires balancing operational demands with complex financial engineering. Not every tax strategy will perfectly align with the specific dynamics of every deal, but the greatest risk is the forfeiture of these opportunities due to a compressed timeline. Tax mitigation and wealth preservation are not post-deal cleanup tasks; they are primary drivers of net transaction value. By engaging advisors and coordinating these actionable strategies before a formal agreement is ever drafted, stakeholders can protect their wealth, help mitigate unnecessary tax friction and step into their transaction with more clarity.

Your Oxford team brings deep experience working with business owners, founders and long-standing trust structures. In coordination with your legal and tax advisors, we apply thoughtful, customized strategies designed to help ensure your wealth transfer plan remains aligned, effective and enduring across generations.

Oxford Financial Group, Ltd. (“Oxford”) is a Registered Investment Advisor (“RIA”) with the U.S. Securities and Exchange Commission (“SEC”) and is headquartered in Carmel, Indiana. Registration with the SEC does not imply a certain level of skill or training. Additional information about Oxford, including our Form ADV and Privacy Policy, is available upon request by calling 800.722.2289 or emailing info@ofgltd.com. The content of this presentation is intended for educational and illustrative purposes only. It should not be construed as investment, tax, or legal advice, nor as a recommendation or offer to buy or sell any security or investment product. The strategies referenced above are illustrative in nature and may not be available, suitable or advisable for every individual, entity or transaction. No strategy discussed guarantees the achievement of any tax, estate planning or transaction objective. Tax and legal counsel should be engaged before taking any action. This material has been prepared using original sources believed to be reliable, but no representation is made as to its accuracy or completeness. The views expressed are those of Oxford as of the date of the presentation and are subject to change based on market, regulatory or economic conditions, which may not occur as anticipated. For full disclosures and disclaimers, please visit https://ofgltd.com/home/disclaimers. OFG-2608-22

CIO Macro Trends: Mind the Gap

The last letter closed on a wager: a chair who had tightened by talking had bought himself time, and the September data would show what he bought it for. The data have now arrived, and they cut in opposite directions, with a hot core consumer price reading on one side and a labor market that has quietly stopped being the problem on the other. Markets responded by pricing a rate hike at this week’s meeting.

Executive Summary

  • Core Consumer Price Index (CPI) inflation surprised to the upside in August at 0.3% month over month, with headline CPI up 0.4%, though the same source data translate into a more benign 0.2% gain in the core Personal Consumption Expenditures (PCE) index that the Federal Reserve actually targets.
  • Financial markets now price a rate hike at the September 15-16 meeting almost in full, plus a further 25 basis points before year end, while some forecasters, including Oxford Economics, call for the Federal Open Market Committee (FOMC) to stay on hold.
  • Nonfarm payrolls rose 162,000 in August against a consensus of 55,000, July’s reported decline flipped to a 21,000 gain and the three-month average climbed to 71,000 from 38,000, comfortably around the 50,000 breakeven pace.
  • Wage growth kept cooling, with average hourly earnings growth easing to 3.1% year over year and the Oxford Economics wage tracker below 3% for the first time in five years.
  • The Beige Book showed activity improving in 10 of 12 districts with no district contracting for a second consecutive report, even as employment rose only very slightly and five districts reported no change at all.
  • The nowcast for third-quarter growth now runs at a 3.5% annualized rate, helped by a 1.1 percentage point contribution from equipment spending that largely offsets a trade drag of more than a point.
  • Consumer sentiment dropped to 47.8 in early September from 51.7, and short-run inflation expectations jumped to 4.6% from 4.0% as gasoline climbed.

The Fed: A Decision on a Knife’s Edge

The FOMC meets on September 15 and 16 with less consensus around the outcome than at any meeting this year. Following the stickier August CPI report, financial markets have moved to price a hike almost in full, along with another quarter point before the end of the year. The rate decision may not even prove the most informative part of the meeting, since the updated projections and Chair Kevin Warsh’s press briefing will say more about where policy goes next, and internal research now suggests the neutral policy rate has risen since the start of the year.

Governor Christopher Waller supplied the clearest map of how a committee member might vote, departing from the chair’s reserved tone to make plain that this is a live meeting: continued progress toward 2% would let him support holding, while inflation coming in hot would have him consider a hike. August obliged with something in between, which is precisely why the meeting sits on a knife’s edge. Markets had already leaned hawkish after the strong August payroll report, penciling in two full hikes by March 2027.

The case for patience rests on a technical point that deserves more attention than it usually gets. Nonmarket services prices, primarily financial services and insurance, accounted for roughly half the increase in core PCE prices in the prior month’s report, and those prices are imputed rather than observed, which means they move for reasons that have little to do with what anything costs. A Bureau of Economic Analysis methodology change due at the end of September should lower annual core PCE inflation by two tenths of a percentage point, with the treatment of stock-trading fees doing much of the work, and this combination could be the support the Fed needs for a protracted hold through the rest of this year and into 2027. Measuring inflation partly by imputing what people would have paid for services nobody billed them for is a reasonable way to build a price index and a difficult way to set an interest rate.

The Beige Book pointed the same direction. The in-house prices index fell for a second consecutive report, consistent with the recent run of moderate inflation readings extending into August, even as a growing number of Federal Reserve officials appear to be running short of patience with inflation that keeps sitting above target. Energy remains the live risk on the other side, since global oil prices surged after United States military strikes on Iranian targets revived fears of supply disruption, and gasoline prices will likely stay elevated without a meaningful end to the war. President Donald Trump’s announcement of access to 65 billion barrels of Venezuelan oil reserves offers no near-term relief, since that figure describes reserves in the ground rather than shippable supply, and Venezuelan production runs at about 7% of United States capacity.

  • Key Takeaway: This is the closest call the committee has faced all year, and the gap between what markets price and what some forecasts assume has rarely been wider. The resolution turns on whether the Fed reads the hot consumer price print or the tamer reading from its own preferred gauge, and a methodology change at the end of September may quietly settle the argument either way.

Inflation: One Gauge Runs Hot, the Other Does Not

August core CPI rose 0.3%, above both estimates and consensus, while headline CPI rose 0.4% as gasoline perked up. The trouble sat in non-housing core services, the category the Fed watches most closely because it reflects domestic demand, where airfares, motor vehicle maintenance and repair, lodging away from home and wireless telephone services all accelerated. Transportation services carry a particular warning, since they suggest energy costs are working their way into a broader set of consumer prices, a risk the central bank will watch closely as the Middle East situation could worsen ahead of the midterms.

Nearly everything underneath offered reassurance. Core goods prices decelerated, with weakness in apparel, some recreational goods and motor vehicle parts, while computer software and accessories declined outright, a detail that matters because those artificial intelligence (AI) related prices carry outsized weight in the PCE measure; tariff effects are adding roughly three tenths of a point to core CPI inflation and should fade from here. Housing came in as expected, and a jobless expansion paired with a rising rental vacancy rate should prevent any reacceleration in the single largest CPI category. Small businesses corroborated the calm, since actual and planned selling price increases held unchanged in August despite the run-up in diesel.

Producer prices told the energy half of the story plainly. The August Producer Price Index (PPI) rose 0.4% with core prices up 0.3%, lifting annual headline producer inflation to 5.4% from 4.8% and core to 4.6%. Energy did the lifting at 4.2% on the month, and another increase looks likely in September, with diesel up nearly 60 cents and gasoline close to 20 cents within the survey window. The passthrough already shows in transportation and warehousing costs, up 2.3% for their largest monthly rise since April. Food prices rose a benign 0.1%, though diesel feeds grocery costs with a lag of up to nine months, so the reprieve looks temporary.

Put the two reports together and the Fed’s own gauge looks considerably calmer than the headline that moved the market. Mapping the CPI and PPI details points to a 0.37% rise in headline PCE prices and a more modest 0.19% increase in the core, a path that would nudge annual headline PCE inflation down to 3.6% from 3.7% while the core holds at 3.3%. Two thermometers hang in the same room, and this month they disagree by enough to decide an interest rate.

  • Key Takeaway: Core consumer prices ran hot in exactly one place, non-housing core services, and that place carries the fingerprint of energy rather than of broad domestic overheating. The Fed’s preferred measure looks tamer, so the September decision may come down to which instrument the committee trusts.

The Labor Market: Solid Enough to Leave the Stage

The August employment report beat everyone. Nonfarm payrolls rose 162,000 against a consensus of 55,000, July’s reported 23,000 decline turned into a 21,000 gain, June moved higher too and the three-month average of job growth climbed to 71,000 from 38,000, still in the neighborhood of the roughly 50,000 breakeven pace. A 40,000 rebound in state and local government employment supplied much of the lift, exactly the payback that the July collapse implied, while manufacturing appears to have turned a corner and job losses in information and financial activities may carry an AI fingerprint. The unemployment rate rose five hundredths to 4.14% unrounded, for the encouraging reason that the labor force and household employment both grew, with participation up two tenths to 62.6%, though the prime-age rate stayed flat.

One strong month does not make an overheating labor market, and the rest of the evidence describes something closer to stillness. Private payrolls in the Automatic Data Processing (ADP) report rose only 38,000 in August, with the three-month average cooling to 60,000 from 107,000 in June. The July Job Openings and Labor Turnover Survey (JOLTS) showed the hiring rate falling to 3.2% from 3.4% while the layoff rate ticked down to 1%, the familiar no-hire, no-fire arrangement. The quits rate slipped a tenth to 1.9%, which is what happens when workers doubt they could find something better. Openings edged up 89,000 to 7.27 million even as June saw a 177,000 downward revision, leaving the ratio of openings to unemployed workers above one and the market roughly in balance.

Layoffs stayed conspicuously absent. Initial claims ticked up 2,000 to 206,000 in the week ended August 29, with announced job cuts from Challenger, Gray and Christmas the lowest for any August since 2022, then eased 1,000 to 206,000 in the week ended September 5, matching a four-week average at the same level. Unadjusted claims now run nearly 14% below year-ago levels, and continued claims fell to 1.774 million, some 7% lower than a year ago. Small firms echoed the reading, with hiring intentions dipping in August only after July had carried them to their highest level in nearly four years.

Wages are the part that matters for policy, and they keep cooling. Average hourly earnings rose 0.3% on the month while annual growth eased to 3.1% from 3.2%, and the broader Oxford Economics wage tracker fell below 3% for the first time in five years. The ADP measure for all workers slipped a tenth to 3.2%, and the only series still trending up covers job changers, a group whose ranks the low quits rate keeps thin. Set 3% wage growth against productivity running above 2% and the arithmetic points down rather than up.

  • Key Takeaway: August was a strong month inside a stable trend, not the start of an overheating. Hiring stays slow, firing stays rare, and wage growth below 3% against productivity above 2% means the labor market has handed the inflation argument back to energy prices and imputed services.

Growth, Trade and the Ledger

The expansion keeps running on productivity rather than payrolls. The Beige Book found activity improving in 10 of 12 districts in the six weeks to August 24, with the in-house activity index easing to 0.74 from 0.80 and no district reporting contraction for a second consecutive report —the longest such streak since mid-2024. Employment, by contrast, rose only very slightly: five districts reported no change, and AI turned up more often in the commentary, boosting efficiency while cutting both ways on hiring, with some districts seeking AI engineers and contacts in Cleveland, Richmond and New York rethinking entry-level and administrative roles. Where wages did rise meaningfully, they rose in construction and manufacturing, the trades the AI buildout actually employs.

The productivity data supply the mechanism. Second-quarter productivity growth held at 1.4% for an annual pace of 2.2%, with manufacturing contributing heavily as a 5.4% rise in output met a 2.9% increase in hours. The more interesting detail sat in the non-financial corporate sector, where capital and technology spending concentrates: productivity there grew 2.2% and has run ahead of the nonfarm business measure since the second quarter of 2025, which may offer an early read on gains spreading to the rest of the economy as adoption widens. Unit labor costs, revised down a tenth to 1.2% annualized, confirm that none of this is coming out of a wage spiral.

Both purchasing manager surveys pointed to steady growth with the same lagging component. The Institute for Supply Management (ISM) manufacturing index eased a point to 54.6 while new orders and order backlogs held well inside expansion and customer inventories stayed in territory that signals firms need to restock. Its employment index slipped 1.6 points to 51.2 yet managed two consecutive months of expansion for the first time since 2022. The services index rose 1.3 points to 55.4, its strongest since February, and a weighted average of the two points to growth above 2% annualized in the third quarter, though the services employment index remained in contraction. Prices went the wrong way on both: manufacturing input costs held at an elevated 71.1 after a post-war peak of 84.6, and the services prices index jumped 2.3 points to 72.6, its highest since August 2022, with respondents naming the Middle East conflict and tariffs.

Trade delivered the paradox this letter keeps returning to. The July deficit widened to $88.6 billion from $73.3 billion, the largest since March 2025, as imports rose 2.8% against a 2.1% fall in exports, and the strength in imports sat entirely in capital goods, where a $14.4 billion rise left the category a staggering 46% above year-ago levels on computers, computer accessories and semiconductors. Net trade looks set to subtract more than a point from third-quarter growth, almost exactly offset by a 1.1-point contribution from the equipment spending those same imports represent. Construction told a two-sided story as well, falling 0.5% in July and dragging the residential investment nowcast to a 3% annualized decline from 1.6%, while business structures improved to a 1.5% decline from 4.1% as data-center construction kept running and power structures picked up. Add it together and the third-quarter growth nowcast now tracks 3.5% annualized. The ledger, as ever, quietly worsens. Treasury reported a $167 billion August deficit against $345 billion a year earlier, an improvement that is entirely a calendar fiction, since the August gap would have come in $9 billion wider on comparable terms. The fiscal year-to-date shortfall of $1.966 trillion sits $7 billion below last year, yet absent the same quirks it would stand $81 billion higher. Corporate receipts have fallen 24.3% under the One Big Beautiful Bill Act, customs receipts managed a 1.3% annual gain and roughly $40 billion of an anticipated $160 billion in tariff refunds has yet to go out the door. Against that backdrop, the President floated $5,000 checks for all adult citizens should Republicans hold both chambers after the midterms, a program costing as much as $1.25 trillion, or 3.8% of gross domestic product (GDP), and exceeding what Treasury will spend this year on defense, Medicare or interest. There is a very low probability the trifecta would allow it.

  • Key Takeaway: Growth is tracking well north of 3% on productivity, equipment spending and a restocking cycle, with jobs contributing almost nothing to the total. The pattern is durable while it lasts, and the fiscal arithmetic keeps deteriorating underneath it in a way no single quarter makes urgent.

The Consumer and Housing: Wealth Holds, Mood Breaks

Consumers are spending like one group and answering surveys like another. The preliminary September reading of the University of Michigan sentiment index fell to 47.8 from 51.7, below the 51.4 forecast, with the assessment of current conditions falling and the view of the year ahead falling harder. Short-run inflation expectations jumped to 4.6% from 4.0% as gasoline climbed, and the long-run measure ticked up a tenth to 3.4%. The split by income keeps widening, since sentiment deteriorated among lower- and middle-income households while rising among upper-income ones, and economists anticipate that the upper tier will carry consumer spending growth of around 2% through the rest of the year.

The spending data are considerably more cheerful than the mood. Consumer credit rose $18.1 billion in July, with nonrevolving credit up $15.3 billion against a more modest $2.8 billion in revolving credit, whose annual growth slowed to 3.6% from 4.1% as the tax-refund tailwind faded. Excluding student loans, nonrevolving credit rose $10.2 billion, essentially an auto lending story. Student loans grew just $0.3 billion in the first month that the borrowing caps and stricter repayment rules under the One Big Beautiful Bill Act applied, and since borrowers need not switch to the new income-driven plan until 2028, the effect will show up only gradually.

Vehicles made the point in the plainest terms available. Sales jumped to a 16.8 million annualized pace in August, the strongest since April 2025 when buyers were front-running tariffs, leaving third-quarter sales tracking 1% above the second. Higher pump prices have tilted the mix toward hybrids, whose share peaked at 17.1% in May against 13.9% in February, and gasoline has averaged above $4 a gallon since mid-July. Fully electric and plug-in hybrids account for just 6.8% of sales after averaging above 9% in 2025. The top fifth of the income distribution buys more than half of all new vehicles by dollar value, which is why sales can boom while sentiment sinks, and the September baseline looks for 16 million sales this year against 16.2 million in 2025.

Housing remains where the cost of higher-for-longer shows up most plainly. Existing home sales fell 2% in August to 3.98 million, down 1.2% from a year earlier, adding downside risk to a forecast of residential investment declining at a 2.1% annualized pace. The more telling signal was inventory, which rose 3.2% on the month and 5.9% over the year, an unusual direction once the spring selling season has passed and a plausible sign that homes are sitting longer, leaving 4.9 months of supply at the August pace. The median price fell 1.7% on the month while holding a 1.6% annual gain, with the forecast still near 2% growth. The cause sits in the bond market rather than at the Fed: after briefly touching 6% before the war with Iran, mortgage rates now run near 6.75%, which has pushed the monthly payment on a median-priced home up nearly $300, or 15%.

  • Key Takeaway: The consumer who owns assets keeps buying cars while the consumer who buys gasoline keeps answering surveys badly, and the aggregate numbers describe neither one accurately. Housing is the clearest casualty of long rates that higher oil prices, heavier public borrowing and a surge in corporate issuance have pushed up regardless of what the Fed decides this week.

Final Thoughts

The question left hanging two weeks ago has an answer, and the answer is that nobody agrees. Core consumer prices ran hot at 0.3%, the labor market delivered a 162,000-payroll gain that removed any excuse for worrying about jobs and markets promptly priced a hike this week plus another before year end. Against that, wage growth slipped below 3%, the Beige Book price index fell for a second straight report and the Fed’s own preferred gauge looks set to come in near two tenths for the core.

Growth, meanwhile, has quietly become the least controversial thing in the economy, tracking 3.5% annualized on productivity, equipment spending and a restocking cycle that owes almost nothing to hiring. That is a comfortable place for an expansion to sit and an uncomfortable place for a central bank, since an economy this strong offers little cover for patience if the next price print misbehaves. Wednesday settles one question and opens several more, and for once the interesting part of the meeting may be the projections rather than the decision.

Oxford Financial Group, Ltd. is a SEC-registered investment adviser. Registration does not imply a certain level of skill or training. The information provided is for general informational purposes only and should not be considered investment, tax, or legal advice. Opinions are those of the author and are subject to change based on market, regulatory or economic conditions. Forward-looking statements are opinions and/or estimates and are not guarantees of future results. Data and opinions are based on sources believed to be reliable, including unaffiliated third parties such as Oxford Economics, but their accuracy cannot be guaranteed. Past performance is not indicative of future results. See important disclosures and disclaimers at https://ofgltd.com/home/disclaimers. OFG-2609-21

A Letter from our CEO & Managing Director, Jeff Thomasson

Greetings to Our Oxford Clients and Friends of the Firm,

With Labor Day weekend behind us and summer almost over, I thought I would drop you a note and share some of my musings as I do from time to time. Of course, as usual, my comments are “my comments” and largely editorial, so if there are any mistakes in my memo to all of you, I own them!

Like many of you, I am often asked, “How’s business?” To be honest, and somewhat surprisingly, our new and current business, as well as our country’s financial markets, have been good to us during 2026. We sometimes scratch our heads about how everything is doing so well given everything happening in the world right now, but thankfully our world, and the world for most of our clients, has been positive. In some cases, very positive.

The business press has repeatedly discussed the “softness of the private equity space,” but given our niche in the private equity sectors in which we play (gladly), we have not seen any softness. As many of you know, we are not recommending or investing in the billion-dollar funds and not competing with those that do; consequently, in the middle-market space, our Aspirational Solutions/Private Equity has been quite steady and performing quite nicely.

As we have discussed previously, there are about seven stocks that seem to continue to drive much of the equity indices, but unlike the tech bust of 25 years ago, these tech companies are making significant profits/cash flow and their investment performance has been driven largely by their momentum and increasing execution of their business models. More to come on this.

Regarding interest rates, you have seen Bo Ramsey’s newsletters from time to time, no doubt. Even if you are only a casual reader of the business press, it looks like we are likely headed for another upward bump in interest rates before the end of the year. So much for transitory views that have been expressed by both sides of the political aisle. Time marches on and we will get past these Fed decisions once they feel that inflation is under control. Perhaps in the first and second quarter of 2027.

Speaking of politics, it would be inappropriate for me to make any comments (either way) surrounding the political landscape and midterm elections. However, one thing that history has taught us is that the markets can be pretty agnostic over the short term regardless of which political party is in office and which ones control the House and Senate. There may be nuances to this view on the edges, but time has shared these views about Wall Street’s performance repeatedly.

Regarding the organizational priorities of Oxford, we have two new board members, two amazing Partners, Jared Nishida and Charles Carter. They are long-time (and wise) Partners and given their common sense, wisdom and relative youth, they will do a great job in leading the organization with the other Board members and Kristina Baron, Bo Ramsey and myself. Please congratulate them if you see them.

Within the firm, just like most companies, we have a variety of initiatives going on at any given time… but, we have several drivers that are key to our routine focus on superb client service. Following are five of those drivers:

  1. “How can we continue to delight our clients with white-glove service and do so endlessly?”
  2. Soon we will be launching a new Brand representation for the firm. This includes our website, collateral, advertising, media presence, logo design and related brand elements. Our Chief Marketing Officer, Alex Neff, is doing an amazing job in this initiative.
  3. Sue McMillen, our Chief Talent Officer and Jarret Blum, our Chief Development Officer, are constantly working on how to make sure our Managing Directors are properly trained as well as spending endless hours on the search for additional Managing Directors in our seven market offices.
  4. Technology and software applications continue to be our number one priority, along with their successful rollout and adoption across ALL of our organization. Given their complexity and the addition of AI, this is a daunting task, but we are excited about conquering this next chapter of our firm’s future to be both efficient and high-touch at the same time.
  5. Continued focus on our leadership training and succession planning for the Partners and the rest of our colleagues. Given our commitment contractually (due to our Delaware Voting Trust) to perpetual independent and private ownership, these core initiatives are vital for the future of the firm.

Well, thanks for listening and I hope that this email finds you well. Please know that if there is anything I can do for you regarding your services at Oxford, an introduction to a friend, a tweak to our business model, a compliment you want me/us to hear or any other topic that might be on your mind, feel free to reach out to me directly. I will personally follow up!

Thank you for your business, your introductions to others and your friendship.

Warm Regards,


Jeffrey H. Thomasson, MBA, CFP®
Chief Executive Officer and Managing Director


Oxford Financial Group, Ltd. (“Oxford”) is a Registered Investment Advisor (“RIA”) with the U.S. Securities and Exchange Commission (“SEC”) and is headquartered in Carmel, Indiana. Registration with the SEC does not imply a certain level of skill or training. Additional information about Oxford, including our Form ADV and Privacy Policy, is available upon request by calling 800.722.2289 or emailing info@ofgltd.com. The content of this presentation is intended for educational and illustrative purposes only. It should not be construed as investment, tax or legal advice, nor as a recommendation or offer to buy or sell any security or investment product. Tax and legal counsel should be engaged before taking any action. This material has been prepared using original sources believed to be reliable, but no representation is made as to its accuracy or completeness. The views expressed are those of Oxford as of the date of the presentation and are subject to change based on market, regulatory or economic conditions, which may not occur as anticipated. For full disclosures and disclaimers, please visit info@ofgltd.com. OFG-2608-39